Friday, May 21, 2010

Launching A New Era In Wealth Management

I am pleased to announce the formation of HORAN Capital Advisors (HCA) in conjunction with Mark Bennett, CFA, Nick Reilly, HORAN Associates and Terry Horan.

HORAN Capital Advisors expands on the larger HORAN organization by expanding on HORAN's wealth management services. The combination of HORAN’s well-established wealth management practice combined with the intellectual capital and depth of experience of HORAN Capital Advisors creates a strong resource for individuals, families, and institutions.

HORAN Capital Advisors expands on the value HORAN provides to current clients while advising on over $550 million in assets. HCA extends the expertise of HORAN’s wealth management practice by providing clients with superior market knowledge and a proven, sound approach to investment solutions.

The foundation for HCA was established by Jack Horan in 1948. By satisfying the needs of their clientele for over 60 years, HORAN Associates has grown to become one of the region’s largest privately held financial services companies. HORAN has over 6,500 clients in 40 states while managing diversified products for more than 500 companies and 170,000 individuals.

To learn more about our thinking and approach to managing wealth for individuals and institutions, visit HORAN Capital Advisors' website and the HORAN organization website.

Horan Capital Advisors
Horan Associates


Wednesday, May 19, 2010

Higher Yielding Bonds Tend To Hold Up Better In Rising Interest Rate Environment

If an investor maintains any cash in a money market/savings account today, they know interest rates are at levels approaching zero percent. Consequently, it does not seem as though rates can go much lower. When (not if) interest rates do begin to trend higher, be it 6, 9 or 12 months from now, the impact on the price or value of bond investments will be negative. As bond investors know, there is an inverse relationship between bond prices and interest rates. As interest rates rise, the price of bonds will decline. In simple terms, the magnitude of the bond price decline is dependent on the maturity length of the bond or bond fund and the coupon yield for the bond.

Fidelity recently published a research report showing the impact on bond returns during one of the toughest periods for a bond investor: 1941 - 1981. During this stretch of time, intermediate treasury rates rose from .5% to over 16%. As detailed below, bonds that had higher rates tended to generate better returns over the early period of the '41 - '81 time period. The reason for this is bonds with higher coupons and or shorter terms returned cash to an investor sooner that could be reinvested at the then higher rates.


As mentioned earlier, the concern with the Fed moving to an increasing interest rate environment is the potential for an investor to experience negative total returns in the bond portion of their portfolio and many investors use bonds as an insulator or shock absorber to counteract volatile equity markets. I believe Fidelity's research article sums up the situation pretty well:
Investors have reason to worry about future prospects for bond returns—history shows that current low yields may be expected to result in below-average performance, especially if interest rates rise. Investors particularly concerned about the possibility of rising rates may want to diversify their fixed-income portfolios into less interest-rate sensitive sectors. However, the great bond bear market of 1941-1981 also offers some more comforting lessons as well. High-quality bonds are much less volatile instruments than stocks, and they do not lose that attribute during periods of rising rates. Even during a prolonged period of rate increases, owning bonds lowered the volatility and improved the risk-adjusted returns of an overall investment portfolio. As a result, investors may not look with much excitement at the near-term outlook for bond returns, but that doesn’t mean they should over-react by shunning bonds altogether.
Of particular concern is record levels of cash continue to pile into bond funds as reported by ICI. The previously reference link also shows investment flow activity after the flash trading market correction from a few weeks ago. In aggregate, investors have withdrawn large sums of money from all types of investment funds, with the largest dollar amount coming out of equity funds. subsequent to the flash trading event. The Zero Hedge website contains a chart of the S&P index graphed with the fund flow data.

For bond investors, pay attention to the maturity (better yet, duration) of the bond or bond portfolio. Additionally, staying invested on the shorter end of the bond curve could minimize the impact that a rising interest rate environment will have on a particular bond or bond fund's price.

Source:

Perspective on the Potential Downside for Bonds
Fidelity Management & Research Co.
By: Dirk Hofschire, CFA
April 23, 2010
http://personal.fidelity.com/products/pdf/perspective-potential-downside-bonds.pdf


Sunday, May 16, 2010

A Lot Of Good Economic News Too

Much of the financial news has been centered on the EU and its dealings with the Greece sovereign debt issue. Rightfully so the debt issue is one that could have consequences beyond Greece itself. On the other hand, quite a bit of good economic news has been reported recently as well.

Industrial Production

  • Industrial production jumped up at an annualized rate of 10.0 percent in April, following an upwardly revised 2.5 percent gain in March.
  • Over the past 12 months, industrial production is up 5.2 percent, its highest growth rate since June 2000.
Consumer Sentiment

  • The University of Michigan Index of Consumer Sentiment edged up in early May, increasing from an index value of 72.2 to 73.3.
  • Both the current conditions and consumer expectations components posted modest increases, contributing to the overall increase.
Retail Sales

  • Total retail sales rose 0.4 percent (nonannualized) in April, following an upwardly revised 2.1 percent jump in March.
  • Over the past 12 months, retail sales have risen 8.8 percent (their highest growth rate since July 2005).
Factory Orders

  • New orders for manufactured goods increased 1.3 percent (nonannualized) in March, following an upwardly revised 1.3 percent jump in February.
  • New orders excluding transportation rose 3.1 percent in March and are now up 15.6 percent over the past year.
  • The I/S ratio for manufactured goods continues to decline from its peak reading of 1.47 months in January 2009 to 1.27 months.
ISM Index

  • The ISM’s Manufacturing Purchasing Managers Index (PMI) continued improve in April, increasing 0.8 index point to 60.4 (its highest level since June 2004), following a 3.1 point jump in March.
  • The new orders index jumped up from 61.5 to 65.7 in April, continuing its rebound from an all-time low of 22.9 in December 2008.
  • The production index rose 5.8 points to 66.9 during the month, marking its eleventh month above the diffusion index growth threshold of 50.
  • The employment index surged to 58.5 its highest level since January 2005.
Nonfarm Payroll Employment

  • Nonfarm payroll employment grew by 290,000 in April, topping expectations for roughly a 200,000 gain. Census hiring inflated April’s figure by 66,000, but private payrolls still increased 231,000 when discounting the government’s boost.
  • Revisions to February and March figures were solid as well, tacking on an additional 121,000 jobs and leaving those months’ respective gains at 39,000 and 230,000.
  • Jobs in goods-producing industries expanded by 65,000, and services expanded 166,000, its largest increase in over three years.
From a stock market perspective, the S&P seems to have held support at its 200 day moving average at around 1,100. The 50 day moving average is now serving as resistance for the index at the 1,174 level. With the index closing at 1,135 on Friday, if it reaches the 1,174 resistance level, that would be a pretty decent return. Additionally, the selling volume seems to be subsiding as it is in a downtrend at this point. A number of investors likely got stopped out during the 1,000 point decline that occurred on May 6 and are trying to reenter the market.


Economic Data Source: Federal Reserve Bank of Cleveland


A Look At The Market Around The Presidential Election Cycle

I have noted in the past that the market, the Dow Jones Industrial Average ($INDU) in this case, tends to follow a pattern around the presidential election cycle. It is believed tougher economic policy is followed early in the presidential election period if necessary. The hope is the economy will recover in time to re elect the party that is in power. If the market follows this same pattern, a sideways trend may be the norm until the 4th quarter of this year with a stronger advance in the pre-election year period.

Given the extent of potential tax increases in 2011 and sovereign debt issues, a strong market advance is not assured next year. In this environment, an investor should consider constructing the foundation of their investment portfolio in high quality companies.


Friday, May 14, 2010

The Two Sides Of Risk

I read an interesting newsletter written by Howard Marks of Oaktree Capital where he opines on two main investment risks: the risk of losing money and the risk of missing opportunity. In the Howard Mark's newsletter, he notes:
You can completely avoid one or the other, or you can compromise between the two, but you can’t eliminate both. One of the prominent features of investor psychology is that few people are able to (a) always balance the two risks or (b) emphasize the right one at the right time. Rather, at the extremes they usually obsess about the wrong one . . . and in so doing make the other the one deserving attention.

During bull markets, when asset prices are elevated, there’s great risk of losing money. And in bear markets, when everything’s at rock bottom, the real risk consists of missing opportunity. Everyone knows these things. But bull markets develop for the simple reason that most people are buying – ignoring the risk of loss in order to keep from missing opportunity – just when elevated prices imply losses later. Likewise, markets reach their lows because most people are selling, trying to avoid further losses and ignoring the bargains that are everywhere.
The entire newsletter can be read at the original post on Zero Hedge's website. Mark's provides some thoughts pertaining to the current market environment as well.


Thursday, May 13, 2010

Dividend Aristocrats Outperforming Year To Date

In a volatile market environment like the one experienced over the last several weeks, investing the foundation of ones equity portfolio in high quality dividend paying stocks can be beneficial. As the below table displays, S&P's Dividend Aristocrats are outperforming the broader S&P 500 Index on a year to date basis through 5/13/2010. The higher quality nature of dividend payers tends to provide a cushion in highly volatile down trending markets.

Data Source: Standard & Poor's

The S&P 500® Dividend Aristocrats index measures the performance of large cap, blue chip companies within the S&P 500 that have followed a policy of increasing dividends every year for at least 25 consecutive years.


Sunday, May 09, 2010

Events Last Week Were An Excuse To Take Some Profits

As typically is the case, the event(s) that precipitates a market correction is typically unforeseen. Last week's 1,000 point plunge in the Dow at mid week was no exception. Not wanting to make light of the cause for the correction, the S&P 500 Index ($INX) seems to have bounced off its 200 day moving average this past Friday.


From a fundamental perspective, bottom up 2010 and 2011 earnings estimates for the S&P 500 Index are expected to total $81.06 and 94.87, respectively. The $94 estimate would surpass the $92 earnings achieved near the market's peak in late 2007. At that point in time the S&P 500 Index traded in the 1,500 area. Is it possible or better yet probable that the market gets back to this level in 2011?

Through the end of April, the only S&P sector trading near its October 2007 high is the staples sector. As the below table indicates, most sectors are still below their highs by double digit percentages. The S&P 500 Index itself remains over 24% below its October 2007 high.


As I noted in October of last year, anecdotal evidence of a pickup in trucking activity seemed evident during an out of town trip. An article from a week or so ago, Riding the rails: Road map to recovery, also cited a pick up in trucking and rail activity as a sign of improved economic activity. Although first quarter GDP of 3.2% came in lower than the 5.6% reported for the fourth quarter of 2009, it was growth nonetheless. From a positive perspective the growth came from the consumer and business (excluding inventory restocking). Longer term, a lack of saving by the consumer is a problem.

In the recent edition of Standard & Poor's The Outlook, they note that, "no bull market since 1949 has lasted fewer than 24 months." So can this bull market run through March of 2011?

Disclosure: Long NSC


Friday, May 07, 2010

Don't Let Government Dictate Whether One Is In Or Out Of The Market

Tom Gallagher, ISI Group's Washington Analyst, provides insight into recent policy action and its future impact on the market in this recent WealthTrack video. His view on government's impact on the market is an interesting one.

As some readers of this blog know, ISI is a highly respected research and strategy group with many of its analyst top rated by independent outside sources. Tom's strategy team team has been rated #1 by Institutional Investor magazine for 7 straight years.

Tom notes investors should expect somewhat lower returns in their equity investments in the coming years. A part of this is a direct result of the government's action in this post bubble period. Tighter credit standards are being forced on financial institutions and consumers are attempting to reduce the leverage on their own balance sheets at the same time. He notes in the video that yield will become an even more important part of an investor's returns in the coming years versus just capital appreciation.

Lastly, Tom makes some interesting comments about the potential long term opportunities that exist in the emerging markets. He cautions there may still be some downside risk in those markets; however, long term value is present.


Thursday, May 06, 2010

Does May 2010 Lead To A Repeat of March 2009

For investors, today's market action may have felt like late 2008 or the first quarter of 2009. One aspect of the 2008 and early 2009 market was investors had an opportunity to reassess their comfort level with the potential volatility associated with equities. Many were questioning whether they should be reducing their equity exposure during that time period. If they stayed the course, they were able to recover a large portion of paper losses during the last 15 months.

In the strong market advanced achieved since March of last year, investors need to be cautious in not letting emotions get in the way of sound investment decisions. If an investor was uncomfortable with the market environment in March last year and today were uncomfortable with their investments due to today's 1,000 intraday market decline, then an investor might want to consider lightening up on equities at this point in time keeping in mind equities are a long term investment choice.

As it turned out though, a majority of today's market decline was the result of an erroneous trade. For the trade in question, a trader selling shares of Procter & Gamble (PG) inadvertently entered the shares in billions versus millions. With Procter & Gamble being a Dow component, the 37% drop in P&G's stock contributed about 170 points to the Dow's decline. 3M (MMM) fell over $18 and represented over 140 points in the Dow's decline.

Without a doubt there are some uncertain market events in play at the moment, specifically events in Greece and the potential contagion in the sovereign debt markets. From a fundamental perspective though, the U.S. market does not seem to be extended on a valuation basis. Bottom up 2010 earnings for the S&P 500 Index are estimated at $81.06. This represents a projected P/E ratio for the S&P Index of just under 14. Top down 2010 earnings estimates are $65.37 and equates to a P/E multiple of 17. The market is not cheap, but it is does not appear expensive either.

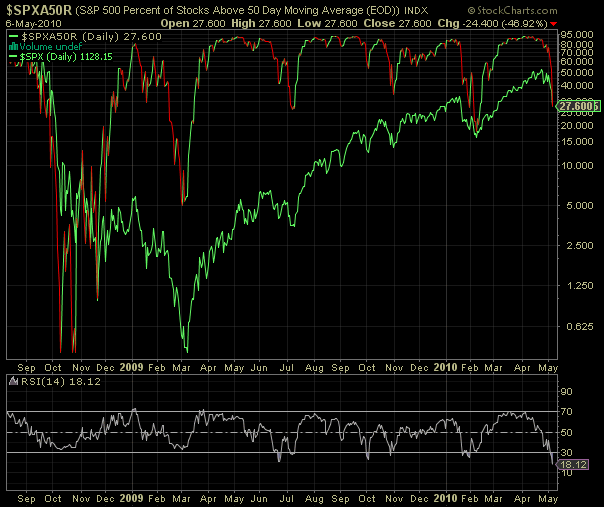
Below are a couple of charts that display a few technical aspects of the market as it relates to the percentage of S&P 500 stocks that are trading above their 50 day and 150 day moving averages. These percentages have decline quite a bit from a few months ago.


For investors then, the sovereign debt issues are certainly events that will continue to impact the markets in the near term. The biggest concern is whether Greece's issues will spill over into other countries like Spain, Italy and Ireland, to name just a few. Investors should keep in mind that it is May and the market is entering a seasonally weak period. Absent of what I think are reasonably sound fundamentals for many high quality U.S. stocks, investors should keep the big picture in mind as it relates to the overall asset allocation for their investment portfolio.


Tuesday, May 04, 2010

Dividend Payers Outperforming Through April

For the first four months of the year, the dividend paying stocks in the S&P 500 Index are outperforming the non-dividend payers, 11.87% versus 10.17%, respectively. The payers have trailed the non-payers in the strong market advance over the last 12-months, however, investors seem to be rewarding the payers now.


Data source: Standard & Poor's


Sunday, May 02, 2010

The Beginning Of May And The Market

Now that it is May some investors are reminded of the adage, "sell in May and go away." Selling in May in 2009 certainly would have left investors on the sidelines during one of the strongest bull markets of recent years.

The tough part with the selling in May strategy this time around is where does an investor go with the cash. As the above table shows, even the low rates of return in the May to October period would be better than money market investments in this market. As a recent Bloomberg BusinessWeek article notes, the May to October period has seen gains in 12 of the last 20 years. The Sell in May and Go Where? article provides an investor with some areas of the market that have tended to perform well during this period, i. e., Health Care and Staples are a couple of sectors.

Source:

Stocks: Sell in May?
Bloomberg BusinessWeek
April 27, 2010
http://www.businessweek.com/investing/insights/blog/archives/2010/04/stocks_sell_in_may.html

Sell in May and Go Where?
The Outlook
By: Sam Stovall
May 5, 2010
http://www.spoutlookonline.com/NASApp/NetAdvantage/mkt/OutlookMarketInsight.do?subtype=OWMO&pc=NET&tracking=NET&context=Company&docId=15400443


Tuesday, April 27, 2010

A Return To Quality

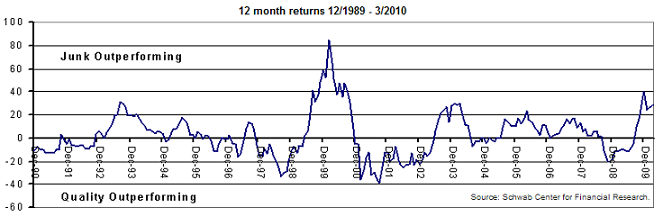
There is no doubting the strong market return that has occurred over the past 12-months. One characteristic of this advance is the fact lower quality stocks as measured by S&P's Earnings & Dividend Quality Ranking have mostly outperformed the higher quality ones.


If one looks at stocks like Abbott Laboratories (ABT) that has an S&P Quality Ranking of A and MGM Mirage (MGM) that has an S&P Quality Ranking of B-, MGM has outperformed ABT and the S&P 500 Index by a pretty wide margin.

In a recent study by Schwab's Center for Financial Research, they show that higher quality tends stocks tend to outperform lower quality stocks in the periods following large outperformance by lower quality stocks.
"When quality underperforms junk by 20% or more, the subsequent 12-month relative return tends to favor quality, on average, by 4.5%. On average, quality has outperformed junk by 11.5% in the year following large junk rallies (over 40%)."
Generally, the highest rating a non dividend paying stock will receive from S&P is A-; therefore, the A+ and A rated stocks tend to consist mostly of dividend paying companies.

If history does repeat itself, returns for higher quality stocks over the course of the next 12-months are likely to outpace the lower quality ones. Currently, lower quality stocks are outperforming higher quality ones by over 28 percentage points. Additionally, given the global economic issues that bubbled to the surface today, i.e., sovereign debt issues with Greece and possibly Portugal, higher quality stocks are likely to be a safer bet than lower quality ones.

Source:

Where Is Quality Hiding
Charles Schwab & Co.
By: John Wightkin, CFA
April 27, 2010
http://www.schwab.com/public/schwab/research_strategies/market_insight/investing_strategies/stocks/where_is_quality_hiding.html?cmsid=P-3549031&lvl1=research_strategies&lvl2=market_insight

Disclosure: long ABT


Saturday, April 24, 2010

More Companies That Increased Dividends Last Week

Catching up on some dividend announcements from this past week: Johnson & Johnson (JNJ), Southern Company (SO), Kellogg (K).


Johnson & Johnson
  • announced a 10.2% increase in the quarterly dividend to 54 cents per share versus 49 cents per share in the same quarter last year.
  • based on 2010 estimated earnings per share of $4.85, the projected payout ratio is 45%. This compares to the 5-year average payout ratio of 41%.
  • JNJ carries an S&P Earnings & Dividend Quality Ranking of A+.

Southern Company
  • announced a 4% increase in the quarterly dividend to 45.5 cents per share versus 43.75 cents per share in the same quarter last year.
  • based on 2010 estimated earnings per share of $2.35, the projected payout ratio is 77%. This compares to the 5-year average payout ratio of 74%.
  • SO carries an S&P Earnings & Dividend Quality Ranking of A-.

Kellogg
  • announced a 8% increase in the quarterly dividend to 40.5 cents per share versus 37.5 cents per share in the same quarter last year.
  • based on 2010 estimated earnings per share of $3.59, the projected payout ratio is 45%. This compares to the 5-year average payout ratio of 47%.
  • K carries an S&P Earnings & Dividend Quality Ranking of A+.


Disclosure: Long interest in JNJ, K


Thursday, April 22, 2010

Investor Sentiment Volatility

This week's investor sentiment survey reported by the American Association of Individual Investors saw a decline in bullish investor sentiment of over 10 percentage points. The bullish sentiment reading was reported at 38.12% versus the prior week's reading of 48.48%. Eleven out of the first sixteen weeks of this year saw changes in the sentiment reading of + or - five or more percentage points. This is a similar number of weeks as were reported in the first four months of 2009. The 8-period moving average of the bullishness reading increased to 40% versus last week's level of 39.6%. This is the fourth consecutive week that the 8-period moving average has increased. The bull/bear spread narrowed to 4% versus 19% last week.


Tuesday, April 20, 2010

Procter & Gamble Increases Dividend 9.5%

For the 54th consecutive year, Procter & Gamble (PG) announced it is increasing the company's quarterly dividend. The new quarterly dividend increases 9.5% to 48.18 cents per share versus 44 cents per share in the same period last year. The estimated payout ratio will equal 48% based on June 2011 estimated earnings of $4.05. The 5-year average payout totals approximately 42%. P&G carries an A+ S&P Earnings and Dividend Quality Ranking.


Disclosure: long interest in PG


Sunday, April 18, 2010

Magnitude Of Rally Not In Uncharted Territory

An interesting chart published by Chart of the Day compares the current post bear market rally to similar periods that occurred in the past.


As Chart of the Day states,
"a 'massive' bear market is defined as a decline of greater than 50%. Since the Dow's inception in 1896, there have been only three bear markets whereby the Dow declined more than 50% (early 1930s, late 1930s until early 1940s, and during the very recent financial crisis). Today's chart also adds the rally that followed the dot-com bust during which the Nasdaq declined 78%. One point of interest is that the current Dow rally has followed a path that is fairly similar to that of the Nasdaq rally that began in late 2002. It is also worth noting that each rally lasted from about 300 to 370 trading days and then moved into a trading range/choppy phase that lasted for a year or more. In the end, the current post-massive bear market rally is by no means atypical."
So are we entering a range bound or choppy phase in the market? Seasonal influences could impact upcoming trading as the summer months approach.


Stock Buybacks: Actions Speak Louder Than Words

Companies in the S&P 500 Index are once again announcing stock buybacks with an increase in buybacks in the fourth quarter last year. Standard & Poor's reports though, the buybacks are essentially offsetting dilution from employee's exercising stock options. S&P reports that most of the companies that had actual reductions in share count in the 4th quarter were found in the consumer discretionary sector.

In looking at the actual dollars expended on buybacks:
  • $47.8 billion in Q4, 2009, $34.8 billion in Q3, 2009 and $24.2 billion in the record setting low period of Q2, 2009.
  • The high point for buybacks occurred in Q3, 2007 when $172 billion of stock were repurchased by companies.
Source: BusinessWeek

As the above chart notes buybacks are on the increase (red line). A true factor worth watching is a substantial increase in dividends paid. The fourth quarter saw a small increase in dividends paid out over Q3, 2009, $49.04 billion versus $47.21 billion, respectively. Dividend payments are a longer term commitment by companies and signal stronger business prospects than buyback announcements. As the below chart notes, cash is accumulating on corporate balance sheets. Commiting to a growing dividend payment would be a positive sign.


Bullish Investor Sentiment Continues Moving Higher

This past week's investor sentiment survey that was released by the American Association of Individual Investors indicates individual investors continue indicating they are more bullish. This past week's bullishness reading was the fourth straight week that the reading came in at a higher level than the prior week. Additionally, the 8-period moving average increased for the fourth straight week as well.

The individual investor bullishness reading was reported at 48.48% versus last week's reading of 42.86%. The 48%+ reading is the highest level reached this year. After Friday's market action and the Goldman Sachs (GS) news, next week's reading may see a dip.


Friday, April 16, 2010

Household Survey Versus Non Farm Payrolls

Which payroll survey is more accurate: the Nonfarm Payroll (Establishment) survey, which shows 162,000 new jobs have been created since December or the Household survey, which shows over 1 million new jobs have been created since December?


Argus Research notes:
"In the year ending August 2003, for example, the Payroll survey originally showed a loss of 463,000 jobs, whereas the Household Survey showed the economy had added 313,000 jobs. At that time, Carnegie Mellon economist Alan Meltzer wrote that the reason for the discrepancy is 'that the number of companies does not remain fixed. In our dynamic economy, old firms die and new ones are born. The Labor Department learns about the deaths quickly, but it takes longer to learn about the births.'"

"In periods of significant downsizing, such as the past two recessions, we think the Household survey is much more likely to be accurate. Using available surveys, we calculate that since 1948, the bottom in Household employment has, on average, occurred 2.9-months before the bottom in Payroll employment. We conclude that U.S. employment bottomed in December."


Saturday, April 10, 2010

Investors Continue Piling Into Bond Funds

One thing investors have a tendency to do is chase returns. Market technicians look at investor fund flow data as a contrarian signal. Given the poor long term return of many stock related investments and the strong bond returns one would think investors might be more attracted to equity investments at the moment. In fact bonds have outperformed stocks over the last 10 and 20 year period and given the low level of interest rates can this possibly continue? In a recent research piece by Fidelity titled, Stocks Anyone? (PDF), it is noted,
"investors actually took money out of stock funds on a net basis during the past year. Meanwhile, the $385 billion of net flows investors put instead into bond funds is more than they ever put into stock funds during a 12-month period—even during the technology bubble of the late 1990s."
Although investors are investing some of their funds into equities, a majority of the inflows are going into bond funds as outlined in the below table.


Additionally, the below charts indicate graphically that investors do have a tendency to chase returns; however, that has not been the case over the course of this past year. Although stocks are outperforming bonds significantly, net flows continue to favor bond funds.


Maybe the significant equity shocks of the last decade (technology bubble and real estate bubble) have resulted in investors taking a longer perspective on equity returns. The below chart compares the 10-year rolling relative performance to fund flows.


This lack of investor interest in stocks is a contrarian sign that suggest equity investors might have a performance advantage compared to bond investors on a forward looking basis.

Source:

Stocks Anyone? (PDF)
Market Analysis, Research & Education
Fidelity
By: Dirk Hofschire, CFA
March 25, 2010
http://personal.fidelity.com/products/pdf/stocks-anyone.pdf


Thursday, April 08, 2010

TJX Cos. Increases Dividend 25%

Earlier this week TJX Cos., Inc (TJX) announced a 25% increase in the company's second quarter dividend. The new quarterly dividend will be 15 cents per share versus 12 cents per share in the same period last year. The dividend payout ratio is projected to equal 19% based on estimated January 2011 earnings of $3.18. The projected payout compares to the 5-year average payout ratio of 16%. TJX carries an S&P Earnings & Dividend Quality Ranking of A+.


Bullish Investor Sentiment Essentially Unchanged

This week's sentiment survey reported by the American Association of Individual Investors saw a small uptick in bullish investor sentiment. The bullishness reading came in at 42.86% versus 41.30% last week. The 8-period moving average has moved higher for the third straight week., increasing to 38% versus 37.2% last week. The AAII survey represents the percentage of individual investors who are bullish, bearish, and neutral on the stock market for the next six months; individuals are polled from the ranks of the AAII membership on a weekly basis.


The Key Is Cash Flow

A recent article appeared in Forbes magazine that focused on the importance of cash flow versus earnings per share. The article, Investing Via Cash Flow, highlighted the success of Martin Saas, chairman of MD Saas. In the Forbes article, Saas notes, "investors get too fixated on the reported earnings...I am religious about cash flow. To me it's the most important number." Saas believes investors should start their review of the financial statement with the "cash flow from operations" statement.
This essentially consists of net income with noncash charges (like depreciation and deferred taxes) added back and cash-draining events (like an inventory pile-up) taken out. Now subtract maintenance-level capital expenditures. The company will tell you its total cap-ex; divining how that divides between maintenance and expansion is a tricky business, but you can strip out discretionary expenditures such as when oil companies increase drilling activity. What you're left with is free cash flow.
Source:

Investing Via Cash Flow
Forbes Magazine
By: Daniel Fisher
March 25, 2010
http://www.forbes.com/forbes/2010/0412/investing-cash-flow-sass-equities-ebitda-cash-does-not-lie.html


Sunday, April 04, 2010

The Impact Of Higher Taxes On Stock Prices

In an effort to look past the health care rhetoric, one aspect of the legislation that we know is coming is higher tax rates. In addition to the higher taxes that are a apart of the new legislation, the Bush tax cuts will expire after 2010 as well. So what does history say about higher taxes and stock prices.

It has been 23 years since capital gains tax rates were increased. The last increase occurred when Ronald Reagan was president. A big part of what Reagan did with taxes was lower the highest marginal tax rate on income from 50% to 28%. However, Reagan did increase the tax rate on capital gains from 20% to 28% beginning in January 1987. What occurred in 1986 was the unleashing of the corporate raider. A recent article in Financial Advisor magazine noted:
It was the age of the corporate raider and folks like T. Boone Pickens. Carl Icahn and Ronald Perelman were making the CEOs of America's biggest companies quake in their stretch limos. With a huge assist from Drexel Burnham Lambert's junk bond department in Beverly Hills, these characters were putting companies into play on a weekly basis. The rest of Wall Street was frantically scrambling to clone Drexel's incredible profit machine and struggling to create their junk bond units to finance LBOs....

When the 1986 tax act became law, these raiders sensed opportunity and took off on a bender that would last for more than two years. Shareholder value was their mantra. Almost every day, they would tee up companies and demand that their boards work over time to quickly complete the deal to give shareholders the full advantage of the soon-to-expire 20% capital gains tax rate. In actuality, most raiders were hoping that a bigger corporation, or so-called white knight, would swoop in and trump their offers.

Did the expiration of the 20% capital gains tax rate in January 1987 hurt stock prices? Hardly. From January to September, equities went crazy. Propelled perhaps by the big cut in income tax rates, the Dow climbed from 1,897 to over 2,700 on August 25 in a frenzy that looked like a runaway train going down Mt. Everest.
The fall out from this junk bond era is well know, but it is worth noting that stocks performed well during this time period. For bond holders, they should have some knowledge of history.
Fed chairman Paul Volcker discerned the all-too-obvious symptoms of an overheating economy and decided he'd had enough of all this nonsense. In April, he jacked up interest rates dramatically, triggering a $100 billion bath for bondholders around the globe.
One aspect that is different this time is income taxes will be on the rise. David Kelly, chief market strategist for J.P. Morgan Funds notes:
  • starting in 2013, the Medicare tax rate on households with income over $250,000 will be increased from 1.45% to 2.35%.
  • a new 3.8% Medicare tax will be introduced for this same group on investment income.
  • the tax rate on dividends and long-term capital gains will increase from 15% to 20% for households earning over $250,000 and with the new Medicare tax, these rates will rise to 23.8% for the same group.
  • Under current tax law, investors get to keep 85% of the income stream from taxable stock market investments. Under this new law this will be cut by 8.8% to 76.2%, reducing the value of the income stream by 10.4% (that is 8.8% of 85%).
  • using a number of broad assumptions, the value of the average stock should be reduced by one quarter of 10.4% or 2.6%—not good obviously, but also not an overwhelming reason to avoid stocks after a 12 month period in which they rose by over 70% and still appear undervalued.
Certainly, an investor's income stream will be impacted by the higher tax rates. The question becomes what are the alternatives to stocks and dividend paying stocks for that matter? If the Fed is preparing to raise interest rates (maybe not until later this year), what will be the impact on bonds? Additionally, with the precarious budget situation with a number of municipalities, tax free bonds may not be the safe haven expected by many investors. In short, don't let the tax tail wag the dog. Some perspective on history is contained in the article, Animal Spirits: The Last Time Capital Gains Taxes Rose.

Source:

Animal Spirits: The Last Time Capital Gains Taxes Rose
Financial Advisor Magazine
By: Evan Simonoff
March 25, 2010
http://www.fa-mag.com/blog/evan-simonoff/5357-animal-spirits-the-last-time-capital-gains-taxes-rose.html

Investment Implications of Health Care Reform
Financial Advisor Magazine
By: David Kelly, chief market strategist for J.P. Morgan Funds
March 22, 2010
http://www.fa-mag.com/online-extras/5344-investment-implications-of-health-care-reform.html


Dividends And Buybacks On The Increase

It is projected that dividends and stock buyback activity will increase in the second quarter of 2010 versus 2Q 2009. According to Howard Silverblatt, Senior Index Analyst at Standard & Poor's:

[expectations are that] second quarter 2010 dividend payments will be higher than second quarter 2009, but still 17% off 2Q 2008. A surge in increases is expected late in the third quarter if companies feel secure in their prospects to commit to future payments. 2010 payments are estimated to be up 5.6% to US$206B. This compares to payments of US$196B in 2009, US$248B in 2008, US$247B in 2007, and US$ 225B in 2006.

With respect to buybacks, Howard Silverblatt notes:
[buybacks are estimated to show] a 37% increase in fourth quarter 2009 over the third quarter 2009, which is 1% less than the fourth quarter of 2008 and 66% less than 4Q 2007. Looking at issues, MSFT (US$ 3.87B versus US$ 1.54B for Q3 2009), KO (US$ 1.51B versus minor) and PG (US$ 1.46B versus US$ 0.01B) returned, with HPQ increasing (US$ 2.7B versus US$ 2.1B), as CSCO (US$ 1.37B versus US$ 1.87B) and DTV (US$ 0.08B versus US$ 0.94B) reduced.

Overall, dollar purchases are ahead by over 39%, but are up 30% void of top issues. Lots of buyback announcements have occurred, but they come down to authorizations and a willingness to get back in the market – actual buys will depend on market conditions. Given that companies are still covering options to prevent dilution...

Source: Standard & Poor's


Friday, April 02, 2010

For Dividend Investors, It Is All About The Cash

As important as the stock yield percentage might be for investors, looking at dividend growth investments is more than simply looking at the yield on a particular stock. Certainly, history shows that a large part of the market's total return is attributable to the dividend return. Since 1926 the dividend component of the S&P 500 has accounted for one-third of the index's total return. An important aspect of focusing on dividends is it provides an investor insight into a company's cash flow.

One of the most important financial statements an investor can review when evaluating a company is the cash flow statement. A recent article reacquaints investors with the importance of this statement. One thing a company can't manipulate is cash. Cash is cash and cash is king as they often say.

As the article, Show Me the Money: Tracing a Firm's Cash Flow, shows, the cash flow statement provides investors with a wealth of information. Under the "financing section" of the statement, investors should pay particular attention to the activity surrounding the stock account. Many companies are once again announcing stock buybacks, but are the buybacks actually reducing the shares that are outstanding? Maybe the buybacks are simply offsetting potential dilution from option exercises.

The Show Me The Money article is timely for investors as many companies are once again focusing on dividends and buybacks as company fortunes seem to have stabilized.


Thursday, April 01, 2010

Dividend Payers Outperform Non Payers In First Quarter Of 2010

During the first quarter of 2010, the dividend payers in the S&P 500 Index outperformed the non dividend paying issues. The outperformance was small with the payers average return equaling 8.37% versus 8.35% for the non payers. In the month of March, no S&P 500 company reduced or suspended its dividend. This compares to March 2009 when 12 companies reduced their dividends.

What is interesting to note about the quarterly performance results is the dividend payers only outperforming month was January when the the payers were down 2.5% and the non payers were down 4.8%. Losing less money in down markets is one key to achieving longer term performance goals. Dividend payers are one way to take advantage of this performance advantage.


Uptick In Bullish Investor Sentiment

This week's individual investor sentiment as reported by the American Association of Individual Investors saw an uptick in bullish sentiment. The bullish sentiment reading increased 8.9 percentage points to 41.3%. This is slightly above the long term average of 39%. Additionally, the less volatile 8-period moving average of the bullish sentiment reading increased to 37.2% versus last week's average of 35.7%. This is the first increase in the 8-period average since January 14th.


Sunday, March 28, 2010

Misconception Surrounding The Importance Of The Asset Allocation Decision

Many investment advisers will indicate that one of the most important variables an investor needs to determine is their asset allocation. The reason behind this has to do with a study completed over 20 years ago by Brinson, Hood and Beebower that indicated that 93.6% of an investor's return is attributable to asset allocation. I wrote a post on this study a few years ago titled, Asset Allocation: Pros and Cons.

In a study reported in the March/April 2010 Financial Analyst Journal titled, The Equal Importance of Asset Allocation and Active Management and written by James Xiong, CFA, Roger Ibbotson, Thomas Idzorek, CFA and Peng Chen, CFA, it is shown that asset allocation is not nearly as important as many believe. In another article in the March/April 2010 FAJ, The Importance of Asset Allocation (PDF), Roger Ibbotson provides a summary of the aforementioned study.

In the summary several important conclusions are noted:
  • many investors mistakenly believe that the BHB (1986) result (that asset allocation policy explains more than 90 percent of performance) applies to the return level (the 100 percent answer). BHB, however, wrote only about the variation of returns, so they likely never encouraged this misrepresentation.
  • In general (after controlling for interaction effects), about three-quarters of a typical fund’s variation in time-series returns comes from general market movement, with the remaining portion split roughly evenly between the specific asset allocation and active management.
  • Do the BHB (1986) time series have any meaning at all in explaining the incremental importance of a specific asset allocation policy? Not necessarily. Perhaps the simplest illustration was given by Mark Kritzman (2006) in a letter to the editor of this journal titled “‘Determinants of Portfolio Performance—20 Years Later’: A Comment.” Kritzman constructed an example in which stock and bond returns moved up and down perfectly together (i.e., were equal to each other each year) while underlying securities did not. The BHB methodology incorrectly ascribed all 100 percent of the return variation to asset allocation, whereas, in fact, all the variation came from stock selection and general market movement.
  • The time has come for folklore to be replaced with reality. Asset allocation is very important, but nowhere near 90 percent of the variation in returns is caused by the specific asset allocation mix. Instead, most time-series variation comes from general market movement, and Xiong, Ibbotson, Idzorek, and Chen (2010) showed that active management has about the same impact on performance as a fund’s specific asset allocation policy (emphasis added).
Investors are encouraged to read the Ibbotson summary to get a clearer perspective on asset allocation decisions.


Thursday, March 25, 2010

Bullish Investor Sentiment Continues To Deteriorate

The market continues to advance in spite of continued weakness in the bullish investor sentiment reading from the American Association of Individual Investors. The weekly readings can be somewhat volatile, but looking at the 8-period moving average can smooth out this volatility. The 8-period M.A. of the bullishness reading has declined for ten straight weeks going back to January 14, 2010. Since this is a contrarian indicator, it will be interesting to see how this plays out over the course of the next quarter.


Data Source: AAII.com


Friday, March 19, 2010

Dow Rally Below Average In Duration & Magnitude

The Chart of the Day has an interesting chart this week that shows the current Dow Jones Industrial Average rally compared to past rallies back to 1900. It may come as a surprise to many investors, but this rally is below average in duration and below average in magnitude of the advance. The Chart of the Day notes:
  • each dot on the chart represents a major stock market rally as measured by the Dow
  • as the chart illustrates, the Dow has begun a major rally 27 times over the past 110 years which equates to an average of one rally every four years.
  • most major rallies (73%) resulted in a gain of between 30% and 150% and lasted between 200 and 800 trading days -- highlighted in the below chart with a light blue shaded box.


Air Products Increases Dividend 9%

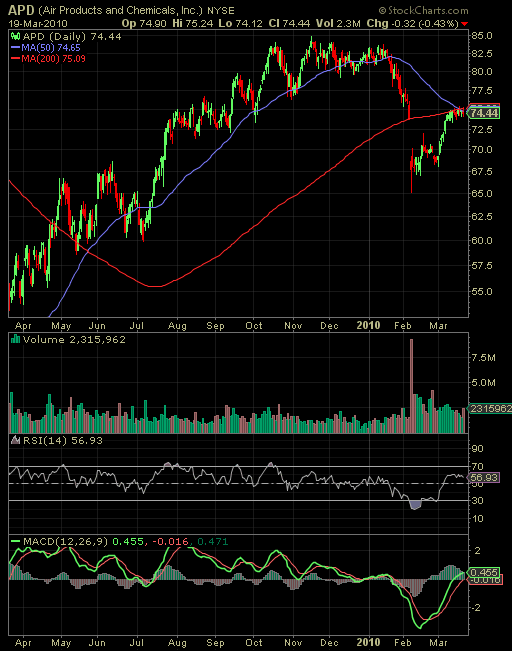
On Thursday Air Products & Chemicals (APD) announced a nearly 9% increase in the company's second quarter dividend. The new quarterly dividend increases to 49 cents per share versus 45 cents per share in the same quarter last year. The payout ratio is estimated at 40% based on September 2010 EPS estimates of $4.92. The 5-year average payout ratio is approximately 42%. The company carries an S&P Earnings & Dividend Quality Ranking of A and the company is one of S&P's Dividend Aristocrats.

As is always the case, investors need to perform their own due diligence before investing in any of the companies mentioned on this site. As it relates to APD, the company has a hostile takeover bid on the table for Airgas (ARG).


Disclosure: long interest in APD


Bullish Sentiment Continues Decline And Market Moves Higher

The individual investor bullish sentiment reading for the week ending 3/17/2010 fell 9.9 percentage points to 35.37%. This level is below the average of the bullishness reading of 39.3%. Since January 13th, the less volatile 8-period moving average of the bullishness reading has declined from 42.9% to this week's reading of 36%. As investors have become less bullish, the market continues to trend higher.


Tuesday, March 16, 2010

Six Notable Dividend Increases So Far In March

Following are six companies in the S&P 500 Index that have increased their dividends so far in March.


Source: Standard & Poor's

Long Interest: GD, PEP, QCOM, WMT


Sunday, March 14, 2010

Fairholme Fund's Bruce Berkowitz Interview

On Consuelo Mack's WealthTrack series, she interviewed Morningstar’s Domestic Equity Fund Manager of the Decade Bruce Berkowitz, founder and lead portfolio manager of the five-star Fairholme Fund (FAIRX). Her interview took place late last year but his advice for investors is invaluable. Berkowitz will explain how he has beaten the S&P by more than 200 percent over the past decade and where he is finding value now.


Better Investing's Most Active Stocks

From time to time I review Better Investing's most active stocks as reported by its members. According to members' recent buy and sell decisions, as reported by a small, informal sampling -- 107 transactions -- for the trailing 4-week period ended March 14, 2010, following are the most active stocks.

Better Investing's most active period ending March 14, 2010Companies Profiles:
  • Petmed Express (PETS)
  • Ford (F)
  • Walgreen (WAG)
  • Stryker (SYK)
  • Life Partners Holdings (LPHI)
  • Jacobs Engineering (JEC)
  • Bank of America (BAC)
  • Oracle (ORCL)
  • General Electric (GE)
  • Berkshire Hathaway (BRK.A)

Long interest: WAG, SYK, BAC, GE and BRK.A & B.


Thursday, March 11, 2010

Bullish Investor Sentiment Rises, But...

Although bullish investor sentiment spiked higher this week, the 8-period moving average continued to decline. The American Association of Individual Investors reported that bullish investor sentiment increased to 45.29% versus the prior week's reading of 35.86%. The bullish sentiment level plus one standard deviation is about 50%. The 8-period moving average of the bullishness reading actually declined to 36.6% versus the prior week's average of 36.9%. This is the ninth straight week the bullish 8-period average has declined.


Monday, March 08, 2010

Market In Denial Phase Of Sentiment Cycle

A reader posted a comment/question on my article about February's performance of dividend payers versus non payers curious if the market sentiment is one where investors are in the denial phase of the sentiment cycle. Several articles today made reference to the fact investors are leery of the market at this stage, in part due to the strong advance off of the March 2009 lows.
Below is a 2-year chart of the S&P 500 Index (SPX) with notations that coincide with a chart that was first publish in 1991 by technical analyst Justin Mamis in a book titled The Nature of Risk. The chart depicts investor sentiment at various stages in the market's cycle.


The market will hit resistance at around the 1,150 level on the S&P 500 Index. Additionally, the recent advance has been occurring on lower volume that may be a sign of investors in disbelief regarding further advance at this point in the cycle.


In short, I believe investors appear anything but confident or enthusiastic at this juncture. Even fund flow data shows investors are placing more money into bond funds than into equity funds.


Monday, March 01, 2010

Dividend Payers' Return Lags Non Payers In February

The average performance of dividend paying stocks in the S&P 500 Index ($INX) underperformed the non payers in February, 4.15% versus 4.74%, respectively. On a year to date basis, however, the payers are outperforming the non payers, 1.57% versus -.24%.

dividend payers versus non payers performance February 2010With respect to dividend actions, February was a much improved environment compared to February of 2009. February tends to be the busiest month for dividend news and the S&P 500 index companies saw 45 increases versus just 30 in the same period last year. Additionally, there were no dividend decreases in February versus 18 decreases in February 2009. For the three month period ending in February, there were 79 positive announcements and just two reductions versus 58 positive announcements and 41 reductions for the same period in 2009.


Source: Standard & Poor's


The Market Is Like A Puzzle

As one puts together a puzzle certain pieces will fit and others won't depending how far along one is in completing the puzzle. Investments aren't much different. Certain types of investments will fit into ones portfolio based on where the economy is in the economic cycle.

I read an interesting post today by Tadas Viskanta, the author of the site Abnormal Returns. His post titled, Play the Ball where it Lies, offers an interesting perspective for investors as they evaluate buy and hold decisions. One premise in the article notes that the markets are rarely "normal" so an investor needs to know why they are making specific investment decisions. At the end of the day, an investor should know why they own what they own. The brief article is a worthwhile read.