Monday, March 19, 2012

The Disconnect Between The Economic Data And Sentiment

Recent unemployment data released by the Labor Department continues to indicate the economy is adding 200,000 jobs per month. This has been the case for the last three months. What is interesting about the continued job growth figures is the GDP growth rate is suggesting a much lower rate of job additions. A recent article in the Wall Street Journal, Piecing Together the Job-Picture Puzzle ($), notes the level of job improvement over the last year would indicate the economy is growing at a 4-5% pace. This projection is based on a study by Arthur Okun and is known as Okun's Law. The Fed has opined on Okun's Law and the relationship between output and unemployment. Mish's Global Economic Trend Analysis site highlights a comment from Madeline Schnapp, Director of Macroeconomic Research at TrimTabs Investment Research:
"Something about the U.S. economy isn't adding up.

At 8.3%, the unemployment rate has fallen 0.7 percentage point from a year earlier and is down 1.7 percentage points from a peak of 10% in October 2009. Many other measures of the job market are improving. Companies have expanded payrolls by more than 200,000 a month for the past three months, according to Labor Department data. And the number of people filing claims for government unemployment benefits has fallen.

Yet the economy is barely growing. Many economists in the past few weeks have again reduced their estimates of growth. The economy by many estimates is on track to grow at an annual rate of less than 2% in the first three months of 2012. The economy expanded just 1.7% last year. And since the final months of 2009, when unemployment peaked, the economy has expanded at a pretty paltry 2.5% annual rate.

How can an economy that is growing so slowly produce such big declines in unemployment?

TrimTabs thinks the problem lies in the heavily massaged BLS employment data and the highly suspect BEA personal income data.

That said, withholding tax data is also messy and not a perfect measure either, but no matter what I do with the data, I can't get to 200,000+ jobs unless a huge percentage of the workforce is suddenly working for McDonalds."
Recently, a number of consumer sentiment releases have turned negative. Last week's University of Michigan consumer sentiment index fell to 74.3 versus 75.3 in the prior month. Expectations were for an increase to 76. Additionally, the IBD/TIPP Economic Optimism Index declined to 47.5 versus 49.4 in February. This decline was the the index's first since August of last year. Readings below 50 indicate consumer pessimism. Both sentiment reports highlight gasoline prices as a prime contributor to the weaker sentiment figures.

From The Blog of HORAN Capital Advisors

TechnoMetrica's (TIPP) president, Raghavan Mayur, notes, "There is a basic disconnect between the media and the American public," he said, adding that coverage of the jobs picture has been too positive. "It's like there are two realities in this country. The report noted that 87.2% of those survey in the poll expect gas prices to top $4 over the next three months and 37.1 expect gas prices to reach over $5. It should be noted that all three of the components of the index worsened. The three components consist of:
  • The Six-Month Economic Outlook: a measure of how consumers feel about the economy’s prospects in the next six months.
  • The Personal Financial Outlook: a measure of how Americans feel about their own finances in the next six months.
  • Confidence in Federal Economic Policies: a proprietary IBD/TIPP measure of views on how government economic policies are working.
There certainly seems to be a disconnect from much of the reported economic data versus consumer/business sentiment.


Wednesday, March 14, 2012

Unlocking The Risk Associated With Stock Concentrations

Various techniques are available to investors in order to customize an effective approach to reducing a concentrated investment. Investors must continually evaluate the investment landscape, concentrated position risk, opportunity cost, time horizon and taxable consequence related to concentrated holdings. We recently prepared a report titled, Unlocking Concentrated Risk (PDF), that we feel is timely for investors as the market and individual stock prices have increased significantly since the market lows in September of 2011.


Wednesday, March 07, 2012

Is The Consumer's Financial Condition About To Worsen?

The consumer is the one important key to economic growth as they account for nearly 70% of GDP. Recent data does show consumer balance sheets have been improving based on the Fed's Financial Obligation Ratio.

From The Blog of HORAN Capital Advisors

Even consumer loan charge offs at commercial banks continue to show significant improvement.

From The Blog of HORAN Capital Advisors

The water on the fire though is the fact consumer delinquencies have recently turned higher. Is this a precursor to a less robust consumer spending environment? The fact gasoline prices have been on the rise as well is likely to reduce the cash available to consumers for discretionary spending.

From The Blog of HORAN Capital Advisors


Markets Retrace Significant Amount Of Losses Since Financial Crisis

The Chart of The Day charting service provides a graphic look at the market recovery for various indices since the financial crisis trough in March 2009.
"For some perspective on the post-financial crisis rally, today's chart illustrates how much of the downturn that occurred as a result of the financial crisis has been retraced by each of the five major stock market indexes. For example, the Dow peaked at 14,164.53 back in October 9, 2007 and troughed at 6,547.05 back on March 9, 2009. The most recent close for the Dow is 12,980.30 -- it has retraced 84.5% of its financial crisis bear market decline. As today's chart illustrates, each of these five major stock market indices have retraced over 78% of their financial crisis decline. However, it is the S&P 400 (mid-cap stocks) and the tech-laden Nasdaq that have recouped all the losses incurred during the financial crisis and currently trade higher than their 2007 credit bubble peak."
From The Blog of HORAN Capital Advisors


Monday, March 05, 2012

Risk On Trade Not Kind To Dividend Payers This Year

The dividend paying stocks in the S&P 500 Index have significantly lagged the performance of their non paying counterparts. The payers return in February and YTD have totaled 3.84% and 8.92% respectively. The non-payers on the other hand have generated February and YTD returns of 5.55% and 14.19% respectively.

From The Blog of HORAN Capital Advisors

One could say the market has been in a "risk on" mode this year and at least since the end of September last year. As we discussed this in our 4th Quarter Investor Letter the "risk on" "risk off" trade has been a common discussion item of late. Investors that desire to track the "risk on" and "risk off" cycles of the market are now able to follow the newly issued exchange traded notes with tickers "ONN" and "OFF". As the below charts show, these ETRACS notes came into existence in late 2011. Until the last few trading days, these indexes have shown the market has been mostly in a "risk on" mode. The question becomes whether the "risk off" trade exhibited over the last two to three trading days is one that will be sustained. If so, the dividend payers might regain some of the ground lost to the non-payers.

From The Blog of HORAN Capital Advisors


Saturday, March 03, 2012

Investor Equity Fund Flows Indicate They May Be Late To The Rally

Mutual fund flow data appears to indicate investors have been late to allocate additional funds to equities in spite of the strong equity market advance since the end of September last year. As the blue bar in the below chart indicates, monthly net flows into equity mutual funds has been negative in spite of the continued advance in the market.

From The Blog of HORAN Capital Advisors

The below chart shows the same data with flows accumulated on a rolling one year basis. Historically, when equity flows have been negative, the equity market returns have not been favorable. During this most recent period though, equity returns have been extremely strong in the face of the negative equity fund flows.

From The Blog of HORAN Capital Advisors

Not until this past month have equity fund flows turned positive. The biggest beneficiary of flows though has been fixed and money market funds.

From The Blog of HORAN Capital Advisors
Source: ICI

From The Blog of HORAN Capital Advisors

From a contrarian standpoint, and taking into account only the fund flow data, investors don't seem to have thrown in the towel and piled into equities.Maybe this market continues to climb the proverbial "wall of worry" until we see investors capitulate and plow into equities.


Sunday, February 19, 2012

$4 Gasoline Has Negative Impact On Confidence And Retail Sales

The recent rise in oil prices and subsequent increase to near $4 per gallon for regular unleaded gasoline is likely to negatively impact consumer confidence and retail sales. The below chart shows the negative influence increasing gasoline prices (inverted on chart) has on consumer confidence.

From The Blog of HORAN Capital Advisors

The negative impact on confidence also negatively impacts retail sales when gasoline reaches $4 per gallon. Note, gasoline prices lead retail sales by one month in the below chart.

From The Blog of HORAN Capital Advisors

Lastly, as noted in an earlier post, declining confidence often translates into weaker equity prices.

From The Blog of HORAN Capital Advisors


Saturday, February 11, 2012

Volatile Equity Market Returns

Absent the significant market contraction in 2008/2009, both the Dow and S&P 500 Index have generated decent returns. For investors though, the equity market pullback during the financial crisis period of '08/'09 remains top of mind. As the below tables show, the year over year returns for these two indices have been pretty strong resulting in 3-year annualized returns in the mid-teens. Unfortunately, the significant decline during the financial crisis has resulted in no return over the four and five year time period.

returns 1 31 2012

The Chart of the Day puts this most recent rally in perspective in their below commentary and chart.
"The Dow made another post-financial crisis rally high Thursday as it approached the 13,000 level. To provide some perspective to the current Dow rally that began back in early October 2011, all major market rallies of the last 111 years are plotted on today's chart. Each dot represents a major stock market rally as measured by the Dow. As today's chart illustrates, the Dow has begun a major rally 28 times over the past 111 years which equates to an average of one rally every four years. Also, most major rallies (78%) resulted in a gain of between 30% and 150% (29.8% to 150.5% to be exact) and lasted between 200 and 800 trading days (9.5 months to 3.2 years) -- highlighted in today's chart with a light blue shaded box. As it stands right now, the current Dow rally (hollow blue dot labeled you are here) would be classified as well below average in both duration and magnitude."
dow rallies

At HORAN Capital Advisors, we believe this heightened volatility is likely to represent the return pattern for investors for the foreseeable future. As such we believe it is important for investors to incorporate a high quality portfolio for their core equity investments. Additionally, making use of so called alternative investments that potentially minimizes downside returns is equally important.

Friday, February 10, 2012

Pick Your Strategist/Advisor Carefully

The below chart was provided by the Wall Street Journal courtesy of Doug Kass.

rosenberg roubini sp chart


Wednesday, February 08, 2012

Congress Desires To Eliminate Tax Deferral Option Of Inherited IRAs

In Congress' effort to continue transportation funding, Senate Finance Chairman Max Baucus (D., Mont.) has recommended the bill include a provision limiting the tax deferral options of inherited IRAs unless the IRAs have been converted to a Roth. In simple terms, currently, inherited IRA beneficiaries are able to withdrawal funds over the beneficiary's life expectancy. Beginning in 2013, the proposed legislation would require most non-spouse inheritors of traditional IRAs to withdraw the entire amount from a traditional IRA within five years. There are a few exceptions that are detailed in a recent Forbes article, Congress May Crush Key Tool For IRA Inheritors. The Forbes article notes, "Let’s hope there’s enough of a public outcry that this legislation doesn’t pass. If it does, owners of traditional IRAs will have one more reason to convert them to Roth accounts. The mark up legislation can be viewed at this link (PDF).


Tuesday, February 07, 2012

January A Risk On Month

As we noted in our fourth quarter investor letter, the new phrase repeated throughout 2011 was “risk on/risk off,” simply defined as buying riskier investments during positive market moves and selling riskier investments during downward moving equity markets. “Risk on” assets include stocks, commodities and high-yield bonds; whereas “risk off” assets include cash, U.S. treasuries and gold. Specifically, in a "risk on" environment, stocks that have higher betas tend to be favored by investors. Higher quality dividend paying stocks tend to move out of favor during these "risk on" phases relative to the higher beta investments.

January was certainly a case in point where "risk on" was the operative strategy. In January the average return for dividend payers in the S&P 500 Index trailed the non payers by 3.30 percentage points.

payers vs non payers 1 2012


Sunday, February 05, 2012

Presidential Election Year Stock Market Return

More times than not, in a presidential election year the stock market has had better performance when the incumbent party wins. As noted in a recent T. Rowe Price report, "the S&P 500 Index has risen in 12 of the 16 election years since World War II. While that’s about the same percentage of all up years in that time, the index had an average gain of 9.2% when the incumbent party won and just 2.2% when it lost, according to Ned Davis Research." The report also notes that the market has declined in two of the last three presidential election years.

From The Blog of HORAN Capital Advisors

Source:

The Stock Market In Presidential Election Years (page 7)
T. Rowe Price Report
Winter 2012
http://individual.troweprice.com/public/Retail/xStaticFiles/Winter2012PriceReport.pdf


Saturday, February 04, 2012

Milton Friedman On Capitalism 32 Years Ago

A two minute excerpt from a 1979 Phil Donahue show where Milton Friedman talks about capitalism and socialism.


Friday, February 03, 2012

Labor Market Only Marginally Better

Although the equity market liked the employment report this morning, the labor market is far from where it needs to be to absorb the jobs lost since the last recession. The 243,000 jobs that were added was the highest in the last nine months; however, the number of employed is far below the level prior to the recession--5.6 million below.

From The Blog of HORAN Capital Advisors

Certainly the addition of 200,000+ new jobs is a positive, but this recovery remains one of the weaker recoveries in terms of job creation. The participation rate remains at a level last reached more than 20 years ago. The employment to population ratio and the average duration of unemployment also remain at problematic levels.

From The Blog of HORAN Capital Advisors


Sunday, January 29, 2012

Stock Buybacks Do Not Benefit Future Stock Performance

In a recent research report by Thomson Reuters they note that a company's stock buyback activity generally does not add value subsequent to the buyback. A reason cited is the fact companies generally have more cash on hand in good economic environments and this tends to be after the stock price has already reflected a more positive operating environment. The report concluded:
"...most companies in the S&P 500 index have not been successful in adding value through stock buybacks in the time frames we observed. The positive correlation between buyback activity and price suggests a combination of poor market timing as well as policies that increase repurchases when firms have more free cash flow. This may be partially explained by the need for officers of public companies to make some use of the cash on hand, including keeping less of it due to the possibility of being taken over. The negative correlation between repurchases and forward returns shows that most buybacks did not pay off within the year after purchase."
Even for the market (S&P 500 Index) overall, the increased buyback activity occurs at ever increasing price levels.

From The Blog of HORAN Capital Advisors

One interesting aspect of the buyback activity at this point in time is it does seem to be at a sufficient level that it makes up for the lack of investor fund flows into equity mutual funds. As the below chart notes, cumulative outflows in equity mutual funds is running at a little over $400 billion dollars since 2006. Buybacks over that same time period total approximately $2.1 trillion through the 3rd quarter of 2011 as reported by Standard & Poor's (PDF).

From The Blog of HORAN Capital Advisors

A few companies were highlighted in the Thomson report as having timed their buybacks successfully. One example is St. Jude Medical (STJ). As the below chart shows, the company tended to successfully execute its buyback on dips in the company's stock price.

From The Blog of HORAN Capital Advisors


On the other hand, Exxon Mobil's (XOM) buyback timing seems to occur after the company's stock price has rallied.

From The Blog of HORAN Capital Advisors

For investors then, buybacks tend not to be a good predictor of future stock price performance. We have written several posts in the past about some of the pitfalls in company stock buyback programs. Ideally, investors should focus on a company's dividend practices. When a company increases its dividend, it is making a long term commitment of its future cash flow; hence, a more significant statement about future earnings prospects.

Disclosure: Long XOM and no position in STJ


Friday, January 27, 2012

Fourth Quarter 2011 Investor Letter

Fortunately for investors, the calendar has turned to a new year and 2012 has gotten off to a strong start in January. As our 4th Quarter Investor Letter notes, 2011 was a flat but volatile year for the market (S&P 500 Index); however, as of 12/31/2011, the 3-year annualized return for the S&P is 14%. Not bad for a 3-year time period. The disparity in valuations between stocks and bonds is near record levels as we discuss in our Investor Letter.

The Letter can be accessed directly from our website at the following link: 4th Quarter 2011 Investor Letter

We hope you find the content of our letter insightful as we look to 2012.


Sunday, January 15, 2012

High Ratio Of Public Debt To GDP Constrains Economic Growth

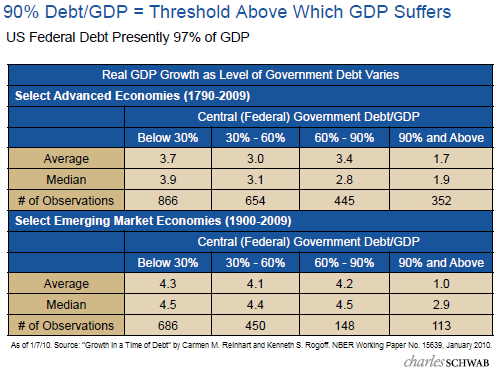
Approximately two years ago Carmen M. Reinhart and Kenneth S. Rogoff completed a comprehensive study, “Growth in a Time of Debt”, which looked at public debt levels around the globe and the resultant impact on economic growth for the respective economies. The study noted the historical consequences of various debt levels relative to an economy's GDP growth with the impact of increasing public debt levels on a country's economy being different for emerging and developed economies. The study authors concluded economic growth does tend to suffer significantly when a country's debt to GDP level exceeds 90%. For some emerging economies, debt to GDP levels over 70% begin to constrain growth. In the U.S. public debt to GDP is now over 90%.

From The Blog of HORAN Capital Advisors

Reinhart and Rogoff noted in their study:
"The simplest connection between public debt and growth is suggested by Robert Barro (1979). Assuming taxes ultimately need to be raised to achieve debt sustainability, the distortionary impact imply is likely to lower potential output. Of course, governments can also tighten by reducing spending, which can also be contractionary. As for inflation, an obvious connection stems from the fact that unanticipated high inflation can reduce the real cost of servicing the debt. Of course, the efficacy of the inflation channel is quite sensitive to the maturity structure of the debt. Whereas long-term nominal government debt is extremely vulnerable to inflation, short term debt is far less so. Any government that attempts to inflate away the real value of short term debt will soon find itself paying much higher interest rates...

...In principle, the manner in which debt builds up can be important. For example, war debts are arguably less problematic for future growth and inflation than large debts that are accumulated in peace time. Postwar growth tends to be high as war-time allocation of manpower and resources funnels to the civilian economy. Moreover, high war-time government spending, typically the cause of the debt buildup, comes to a natural close as peace returns. In contrast, a peacetime debt explosion often reflects unstable underlying political economy dynamics that can persist for very long periods."
Finally, as the below chart shows, debt levels in Europe (emerging and developed) and the U.S., have seen significant growth since just 2003.

From The Blog of HORAN Capital Advisors

An important outcome of these higher debt levels will be how each country decides to reduce its dependence on debt (balance governmental budgets), while at the same time not implementing policies that constrain private sector growth.


The Dangers Of Leveraged ETFs

From time to time questions arise about using leveraged ETFs in one's portfolio strategy. We caution longer term oriented investors to not use these type of ETF investments. For example, if an investor believes the market will rise in the near term, why not consider a two or three times ultra bull ETF. In this case an investor would expect the ETF to generated two or three times the return of the underlying index. Well, for an investor, it is not that simply due to how the math calculation works. Let's look a 2x's ultra long or bullish ETF example.
  • Lets assume at the beginning of day 1 an index is trading at $100. At the end of the day the index closes at $90 or down 10%. The leveraged ETF would close at $80 or down 20%.
  • On day 2 the index rises to $99 or up 10%. The 2x's leveraged ETF would increase to $96, that is $80 * 1.20=$96.
  • Over the two day period though the index is down 1% while the leverage ETF is actually down 4% or four times worse than the index return versus the expected two times worse return.
From The Blog of HORAN Capital Advisors

One problem with many of these leverage ETFs is they reset daily and individual investors generally do not rebalance their portfolios on a daily basis. So as one can see, the performance of these ETFs over a period longer than one day can differ significantly from their stated daily performance objectives. More on this topic can be found on the SEC's web site in an article they wrote titled, Leveraged and Inverse ETFs: Specialized Products with Extra Risks for Buy-and-Hold Investors.


Saturday, January 07, 2012

Forecast For 2012 By Ed Hyman And Bob Doll

The recent WealthTrack interview conducted by Consuelo Mack features Ed Hyman, Chairman and Founder of ISI Group, and Bob Doll of BlackRock. Ed Hyman has been rated the #1 economist by Institutional Investor for 32 years running. Both strategist see the U.S. as the best house in a bad neighborhood for investors. Hyman notes the US economic data has been better, but not great, every week for the past three months. For more on their insights for 2012, readers can view the below video.


Monday, January 02, 2012

Equity Risk Premium Near An Extreme

The equity risk premium recently reached levels last seen at the height of the financial crisis in 2008. The high risk premium level suggests equities are attractive at this point in the market cycle. One key is whether corporate earnings can continue to make new record highs in 2012. Earnings growth is expected albeit at a slower rate than achieved in 2011. Given the level of stock buybacks and more importantly, company dividend increases, it seems equities could do well looking forward. The buyback and dividend actions by companies provide some level of favorable insight into company earnings expectations. As is typically the case, unforeseen events can derail a favorable market environment. The known risks are numerous and will continue to result in somewhat volatile price action (sovereign debt issues, political rhetoric in the U.S., dealing with the U.S. budget deficit and debt levels, just to name a few), but our forecast suggests equity prices should end 2012 higher.

From The Blog of HORAN Capital Advisors


Sunday, January 01, 2012

Dogs Of The Dow For 2012

The Dogs of the Dow in 2011 significantly outperformed the Dow Jones Industrial Average Index (DJIA) and the S&P 500 Index on a price only basis in 2011. The Dow Dogs returned 12.2% versus the DJIA return of 5.5%. The S&P 500 Index was essentially flat on the year.

The Dow Dog strategy consists of selecting the ten stocks that have the highest dividend yield from the stocks in the Dow Jones Industrial Index (DJIA) after the close of business on the last trading day of the year. Once the ten stocks are determined, an investor would invest an equal dollar amount in each of the ten stocks and hold them for a year. The strategy has generated mixed results over the years.

The Dogs of the Dow for 2012 have two new additions, Procter & Gamble (PG) and Kraft (KFT). The two stocks eliminated from the Dow Dogs are Chevron (CVX) and McDonald's (MCD). Below is a list of the Dogs of the Dow for 2012.


Saturday, December 31, 2011

Moderate Inflation Benefits Equities

During moderate periods of inflation, equities tend to generate decent performance results. I posted the below chart in a post, Where To Invest In An Inflationary Environment, in mid 2010 that details the performance of various investment categories based on different inflation ranges going back to 1972.

From The Blog of HORAN Capital Advisors

Since mid year 2010 inflation has been trending higher with the latest year over year report showing inflation running at nearly 3.5%.
From The Blog of HORAN Capital Advisors

The blog at Crossing Wall Street selected the below chart as the Overlooked Chart of the Year. The chart compares the S&P 500 Index to the market’s expectation for inflation (the 10-year TIP spread). Of late, there has certainly been a high correlation to higher inflation expectations and the S&P 500 Index return.

From The Blog of HORAN Capital Advisors

Determining the true level of inflation is also a frequent topic. The Shadow Government Statistics (SGS) site makes an effort to track data on indexes when the calculation methodology is changed. In 1990, the CPI calculation was changed and a comparison of the current CPI versus the 1990-based calculation can be found on the SGS site.


Friday, December 30, 2011

Equity Performance in 2011

With the close of trading today, following is a quick look at the 2011 price performance of a few select equity markets around the globe.

From The Blog of HORAN Capital Advisors
Source: Reuters


Monday, December 26, 2011

Watching The Valuation Of Dividend Payers

The investment mantra this year has been to focus on dividend paying stocks. Over the long run, payers have had a tendency to outperform the non payers and this has certainly been the case this year. On the other hand though, valuations do matter and the below chart provides investors with a cautionary view of simply buying "any" investment that has yield.

From The Blog of HORAN Capital Advisors


Saturday, December 17, 2011

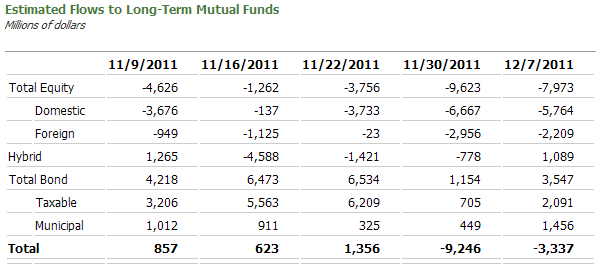
Investors Favoring Bond Funds

Recent mutual fund flow data shows investors continue to favor bonds over equities.

From The Blog of HORAN Capital Advisors
Source: ICI
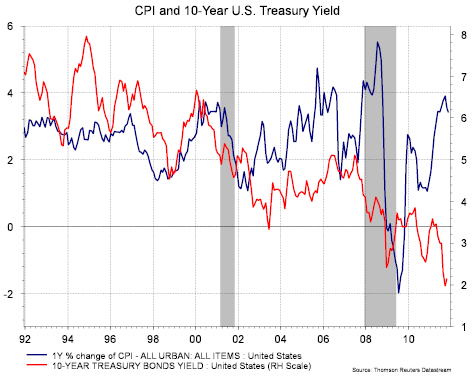
With the sovereign debt issues in Europe top of mind for investors, they continue to bet the best of the worst fixed income investments are U.S. Treasuries. One risk investors face with fixed income investments is the negative impact of a rise in rates. The 10-year U.S. Treasury yield is a meager 1.85% in spite of the fact the consumer price index is running at a year over year rate of 3.4%. Investors are in for a rude awakening when rates do begin to move higher (bond prices have an inverse relationship to the move in interest rates).

From The Blog of HORAN Capital Advisors


Thursday, December 15, 2011

Fragile Employment Market

The improvement in the unemployment rate earlier this month was certainly positive on the surface. The rate declined to 8.6% from the previously reported 9%. The improvement though came largely from the 300,000 individuals that simply stopped looking for a job. As a result, these additional people are not counted among the unemployed. As the below chart shows, the number individuals not in the labor continues to rise.

From The Blog of HORAN Capital Advisors

This fragile state of the consumer also shows up in the number of individuals on food stamps.

From The Blog of HORAN Capital Advisors


Sunday, December 11, 2011

Dividend Aristocrat Changes For 2012

Going forward S&P has changed the methodology on how they determine which companies qualify as Dividend Aristocrats. S&P notes they will only count regular dividend payments when determining the calendar year total dividend payments of a company. Special cash dividends will no longer be considered.

The table below contains a list of Standard & Poor's Dividend Aristocrats for 2012. The rebalance will take place at the market's close on December 16, 2011. The green highlighted companies are the additions and the yellow highlighted company is the deletion. S&P has added ten new Aristocrats while eliminating one, CenturyLink, Inc.


Barron's Income Investing Blog highlights some year to date dividend comments from Howard Silverblatt, Senior Index Analyst for S&P:
  • Year-to-date (YTD) dividend payers in the S&P 500 have returned 1.72%, compared to the non-payers loss of 4.63%.
  • The actual dividend payment YTD is up 16.2%.
  • The indicated dividend rate (based on the current rate) is up 16.8% YTD, but still off 4.9% from the June 2008 high.
  • From 1995 the S&P 500 indicated dividend yield has averaged 43% of the U.S. 10-year Treasury note, the current rate is 105%.
  • 215 issues have a current yield higher than the 10-year Treasury.


Disclosure: Long ABT, APD, ADP, BDX, CTL, CB, BEN, GPC, ITW, JNJ, LOW, MCD, NUE, PG, WMT


The Need For Cutting Spending In Washington

Much of the rhetoric coming out of Washington is focused on the need for more revenue, specifically from individual tax payers. The millionaire tax discussion is emblematic of this focus. As the below chart shows though, individual tax receipts into the U.S. Treasury are up 22% on a year over year basis through the end of September with overall receipts up nearly 7%.

From The Blog of HORAN Capital Advisors

Additionally, individual receipts for the government are near the level received in 2007. On the other hand, government spending has grown 2% on a year over year basis.

From The Blog of HORAN Capital Advisors

From The Blog of HORAN Capital Advisors

In short, Washington needs to have a greater focus on cutting spending, while at the same time promoting policies that are favorable to businesses to enable greater employment growth.


Sunday, December 04, 2011

Future Strength In Retail Sales?

A common view from pundits on the strength in retail sales on Black Friday and Cyber Monday is much of the increase represented consumers buying forward. In other words, the common take on the strong sales report was it likely won't continue into December. If history is any guide, the below chart might indicate additional retail sales growth is likely for the balance of the weeks leading up to Christmas.

From The Blog of HORAN Capital Advisors

The dollar value of total cyber sales increased 22% versus last year and dollars spent per buyer increased 9%.

From The Blog of HORAN Capital Advisors

Since consumers account for 70% of GDP, these retail sales figures suggest Q4 GDP could surprise on the upside.

Source:

comScore
Cyber Monday Spending Hits $1.25 Billion to Rank
as Heaviest U.S. Online Spending Day in History

November 29, 2011
http://www.comscore.com/Press_Events/Press_Releases/2011/11/Cyber_Monday_Spending_Hits_1.25_Billion


Many Corporate And Consumer Positives

I noted in a post a few weeks ago about the positive trend in the JOLTS (Job Openings and Labor Turnover Survey) report which was released by the US Department of Labor and indicated job openings, as of the end of September, were at their highest level since 2008. Additionally, jobless claims, a key leading indicator, have now moved below 400,000 on a four-week moving average basis, which signifies an improving job market. The ADP Private Payroll report showed a 206,000 job gain in November, well above estimates and the best reading since March 2010. The broader November jobs report indicated the US economy added 120,000 jobs and that the unemployment rate declined to 8.6% from 9.0%, the lowest rate since March 2009.

On the corporate side the October Index of Leading Economic Indicators rose 0.9%. This was the sixth monthly increase in a row. Nine of index’s 10 components saw increases for the first time since May of 2003. As noted by the conference board,
“the LEI is pointing to continued growth this winter, possibly even gaining a little momentum by spring. The lack of confidence has been the biggest obstacle in generating forward momentum, domestically or globally. As long as it lasts, there is a glimmer of hope.”
From The Blog of HORAN Capital Advisors

Other positive corporate data points:
  • Industrial production rose 0.7% in October
  • Chicago PMI rose to 62.6 from 58.4, a seven-month high, and the new orders component rose to its highest level since March at 70.2
  • The Institute for Supply Management’s (ISM) Manufacturing Index rose to 52.7, the highest level since June
  • New orders increased to 56.7 from 52.4
Lastly, a number of our articles are republished by SeekingAlpha. Yesterday they republished our post, Market Driven By Emotions Versus Fundamentals. What was interesting is the number of bearish comments (contrarian indicator?) and one comment about the macro environment having a controlling influence on the markets direction.

The biggest potential market negative seems to be the debt crisis in the Eurozone. On the other hand, the economic environment in the U.S. continues to improve in spite of the downward revision to third quarter GDP from 2.5 to 2.0. The revision was largely attributable to a decline in private inventories, which reduced overall GDP by 1.55 percentage points. This type of revision likely means higher growth in Q4 and into early 2012 as businesses have to rebuild inventory levels to keep up with what appears to be improving demand. Our post, Market Driven By Emotions Versus Fundamentals, details some of this demand by touching on the strength in retail sales on Black Friday and Cyber Monday.

From The Blog of HORAN Capital Advisors

From The Blog of HORAN Capital Advisors

There are many positive data points for investors to consider. Certainly the issues in Europe, not to mention in Washington, are not to be made light of. However, the magnitude of the market's advance last week might be some indication of the attractiveness of U.S. equity valuations. Market volatility is high though, so investors should take a disciplined approach if they are building equity positions.


Friday, December 02, 2011

Market Driven By Emotions Versus Fundamentals

I write this shortly after the Dow Jones Industrial Average rockets higher by nearly 500 points, or 4+%, in just one day, I think back to the concerns raised in recent interactions with some investors expressing concern about the market’s volatility. In August and September, 40% of the trading days in the S&P 500 Index saw daily price swings of plus or minus 2%. This level of volatility was last seen in the early 1930’s. Increasingly, the market seems to be trading more on emotion than on company fundamentals. The rally at the end of November was fueled by the announcement that central banks around the globe would provide a liquidity back stop for the European debt issues. The European crisis is contributing to investors trading on short-term emotion while they worry about a repeat of the negative performance seen in 2008 and 2009. One can certainly see similarities; however, we believe there are more recognizable and important differences.

Liz Ann Sonders, Chief Investment Strategist at Charles Schwab noted in a recent report,
“the problems in the eurozone are nothing new: too much debt from eurozone member countries to over-leveraged European financial institutions. Adding to the woes is the lack of global competitiveness among many of the zone's members, thanks to the tying of 17 vastly different economies and policies to one (too-strong) currency. The lack of a single fiscal authority within the eurozone that's capable of enforcement or supervision has allowed the problems to fester and the can to be continually kicked down the road (emphasis added).”
There are many differences in Europe’s problems now and the subprime crisis in the U.S. in 2008. On the positive side, much was learned from the crisis in the U.S. and one outcome is the banks in the U.S. are much better capitalized today. Additionally, the crisis in Europe is one of a top down crisis versus the U.S. crisis which started at the bottom with Lehman Brothers, etc. In short then, European governments have a little more time in crafting a solution.

For investors, we recommend focusing on the fundamentals both economically and at the company level. Economically in the U.S., the data continues to come in better than expected. The November ISM manufacturing index report was stronger than expected (52.7 vs. 51.8) and joins a growing list of indicators that suggest moderate economic growth in the fourth quarter of around 3%. Retail sales on Black Friday exceeded expectations and cyber Monday sales were up a better than expected 24%. The labor market continues to show improvement as can be seen in the below charts: ADP’s Private Employment change for November continues to show improvement and announced corporate layoffs continue to decline.

From The Blog of HORAN Capital Advisors

From The Blog of HORAN Capital Advisors

At the company level, valuations for U.S. equities continue to look more attractive. The below chart represents a broader market P/E measure. The NIPA P/E ratio measures earnings from the GDP calculation and divides it into the S&P 500 Index. Using this measure, valuations are at levels last seen in the early 1980’s. In addition to attractive P/E valuations, corporate balance sheets have record levels of cash. This cash is being returned to shareholders in the form of higher dividend payments and stock buybacks.

From The Blog of HORAN Capital Advisors

In conclusion, the economic data continues to come in better than expected and stock valuations are attractive. Certainly, the news coming out of Europe is going to be market moving and volatility will likely remain high. However, in the longer term, company fundamentals will be the ultimate guiding force for future equity valuations and fundamentals look strong.