Sunday, October 02, 2016

More Signs Of An Earnings Recovery Unfolding

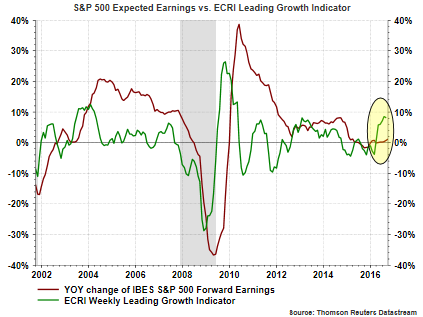
As I have noted in recent posts, an earnings recovery seems to be unfolding. Increasingly, more data continues to point to this earnings recovery over the course of the next twelve months. On Friday, the Economic Cycle Research Institute released data on its proprietary Weekly Leading Index. A variation of this same index is the Leading Growth Index (WLIg). As the following chart shows, the WLIg turned positive in March. Importantly, earnings growth tends to follow changes in the WLIg and recent positive equity market returns may be anticipating an improvement in both the economy and earnings.


Two variables that led to the earnings headwinds in 2015 were the strong U.S. Dollar and the contraction in oil prices, both of which had a negative impact on a number of sectors in the economy. Brent Crude equaled $36 per barrel at the end of 2015 and closed in September at $46 per barrel. Oil prices are likely to remain volatile; however, OPEC’s announcement at the end of September of a production cap (cut) provides some desire by OPEC to see some balance in the supply and demand for oil. This potential balance will be favorable for companies exposed to the energy sector of the economy. As a caution though, in the early 1980’s, OPEX cut supply and then saw oil prices fall 40% as other producers increased supply in order to capture market share. In fact, a similar dynamic could play out this time as the Baker Hughes rig count has increased from 408 in May to 481 in August.


Sunday, September 25, 2016

The Risk Of Dismissing The Data: The TED Spread And Baltic Dry Index

No single variable or statistic provides clear insight into the future direction of the economy or stock market. When a data point does not fit ones narrative though, justification to eliminate it seems to be gaining among some strategists. Recently, the market has seen a fairly significant spike in LIBOR and a resultant increase in the TED Spread, i.e., 3-month LIBOR minus 3-month Treasury.


Thursday, September 22, 2016

Sentiment: Investors Not Believing The Rally

This morning the American Association of Individual Investors released their Sentiment Survey showing a 3.1 percentage point decline in bullish sentiment to 24.8%. The bullish sentiment reading reported by individual investors remains below the -1 standard deviation level of the sentiment measure which is 28.3%.The 8-period moving average of the bullish reading declined as well to 29.6%. 

A vast majority of the decline in bullish sentiment showed up in bearish sentiment (+2.4 percentage point increase) with a net impact of widening the bull/bear spread to -13.5. This is the widest the bull/bear spread has been since late May when the spread was -14.8. Since that point in May the S&P 500 Index is up 5.6% on a price only basis. As individual investors continue to doubt the markets this year, they continue to move higher nonetheless.


Monday, September 19, 2016

Heightened Market Volatility Would Favor Low Volatility Strategy, But It Looks Expensive

A little more than a year ago we wrote about the outperformance of the low volatility strategy versus a more risk on/high beta strategy. At that time it was noted low volatility could persist; however, if the broader market reached new highs, the high beta strategy would likely outperform low volatility. This has essentially played out and as the calendar turned to 2016 the early year market pullback saw the high beta strategy succumb to significant selling pressure and was down 20% into the February low, almost twice the broader market's beginning of year decline. Once the market began recovering from the February low though, high beta has outperformed the low volatility strategy, 25% versus 9%, respectively.


Sunday, September 11, 2016

The Dogs Of The Dow And The Risk With Exchange Traded Notes

Three quarters through the year, the Dogs of the Dow strategy continues to be a winning one, outpacing the Dow Jones Industrial Average and the S&P 500 Index by nearly three times. The average return of the 2016 Dogs of the Dow equals 16% versus the Dow Index return of 5.7% as of Friday's close. As noted in earlier posts, the Dogs of the Dow strategy is one where investors select the ten stocks that have the highest dividend yield from the stocks in the Dow Jones Industrial Index (DJIA) after the close of business on the last trading day of the year. Once the ten stocks are determined, an investor invests an equal dollar amount in each of the ten stocks and holds them for the entire next year.


With the popularity of indexing, some investors have pursued the Dow Dogs strategy via an exchange traded note, the ELEMENTS "Dogs of the Dow" Linked Note (DOD). The return of this note has varied greatly from the performance of the Dogs of the Dow themselves. There are peculiarities with these types of exchange traded products investors should be aware of. More detail on the risk of exchange traded notes can be read here. Two important ones are the fact these investments are essentially bonds of the sponsor of the exchange traded note. In the case of DOD, the issuer is Deutsche Bank AG and an investor in DOD has unsecured credit exposure to Deutsche Bank AG. Secondly, the return on these notes are 'based' on some underlying index or basket of investments. In the case of DOD the ETN's return is based on the Dow Jones Select 10 Total Return Index. Because the issuer is not required to issue more shares of the ETN, the price of the ETN can diverge from the value of the underlying Index and in some cases the divergence is significant. This has occurred with DOD as can be seen in the below chart.


Year to date through early June DOD was up nearly 60% while the underlying Dow Jones Select 10 Index was up only 11.3%. As is typically the case, the large premium at which DOD traded quickly narrowed to the actual return of the underlying index.

Lastly, in this low interest rate environment, investors have a heightened focus on income generating equities. From a total return perspective though, the Dogs of the Dow strategy has had mixed results from year to year.


Friday, September 09, 2016

Transports Leading Industrials A Bullish Market Signal

As early as about six weeks ago, some technical strategists were projecting a near trigger of the Dow Theory sell signal. In short, when the Dow Industrials and the Dow Transport Indexes are in an uptrend together, i.e. higher highs and higher lows, the market is in a bull market uptrend. Conversely, when both indexes are making lower highs and lower lows, a bear market trend is in place or developing. If one sees divergence in the indices, this can be a signal of a change in direction of the market and this was occurring in July of this year when the transports were weakening.

As of the close yesterday though, the year to date return of the transport index return now surpasses that of the Dow index return as can be seen on the below chart. The transport index weakness in late July has been quickly reversed in August and early part of September.


Additionally, positive chart setups have triggered which portend potentially higher prices ahead for both indexes. For the transports an inverted head and shoulders pattern has triggered with an upside target price of about $162 and cup and handle trigger with a lower target than the inverted H&S trigger of $150. Additionally, in spite of the near sideways trading action in the Dow Industrials Index, bull flag formations are in play and are suggestive of potentially higher prices as well.


The industrial and transport segments of the market seem to be indicating an improvement in the operating environment over the next 6-12 months. If earnings prospects continue to improve, as we have discussed in earlier posts, the odds of higher equity prices over the course of the next year seem likely.


Friday, September 02, 2016

Another Month Of Equity Outflows

Individual investor sentiment continues to show a low level of bullishness and this has translated to continued outflows in equity mutual funds and exchange traded funds. Almost a month ago I noted the strong outflow from equity funds and ETFs that occurred in July and this selling trend continued in the month of August.


The outflows have caused assets in equity mutual funds to decline while equity ETF assets have increased on a year over year basis as of the end of July. The increase in ETF assets is largely due to the strong equity market returns from a year ago, for example, the S&P 500 Index is up over 12%.


Sunday, August 28, 2016

Higher Oil Prices Must Contend With Too Much Inventory

Crude oil prices spiked above $50/bbl in early June and have fallen back to $47/bbl as of Friday's close. The high $47 level remains above the early August low of $39.52. Further weakness in oil prices is likely as a result of stubbornly high crude oil inventories (excl. the Strategic Petroleum Reserve.) On Wednesday last week, the Energy Information Administration (EIA) reported weekly inventories increased 2.5 million barrels and is a reversal of the 2.5 million barrel decline in the prior weekly report. Not that one or two weekly reports tell the entire story, but, as the below chart shows, inventories remain at very elevated levels and prices are not likely to move higher until this elevated inventory is reduced.


Saturday, August 27, 2016

Income Focused Investments Continue To Show Weakness

Janet Yellen's Jackson Hole comments on Friday did not do any favors for the performance of income focused investments. The Fed chairman's comments($) led market participants to believe a rate hike for September is back on the table and at least more likely in December. The rate hike fear continues to put downward pressure on income focused investments which some investors view as bond substitutes. So far in the month of August the SPDR Dividend ETF (SDY), the iShares US Real Estate ETF (IYR) and the SPDR Utilities Sector ETF (XLU) are all underperforming the broader S&P 500 Index. Also, for the month of August these three ETFs are showing negative total returns with XLU down 2% on Friday alone.


The site, ETF.com, reported the utility sector ETF was among the top 10 ETFs experiencing outflows for the week, withdrawals totaling $263 million.


Monday, August 22, 2016

What A Difference A Day Makes: The Calendar Roll

The S&P 500 Index was essentially flat today, down .06%; however, an investor's one year price only return will increase over three full percentage points from last Friday's close to today's close. For an investor invested in the S&P 500 Index, Friday's (8/19/2016) one year price only return equaled 7.28% and one day forward to Monday's close, the investor's one year return increases to 10.74%. The reason for this is the calendar rolling forward one day, weekends result in some nuances, and August of last year was a volatile month to the down side for the market and this is contributing to the magnitude of the change in return.


This same impact is resulting in large spikes in the one year rolling return for energy as energy prices were in the upper $30 range versus today's $47.41. As time moves forward to year end, energy was falling into the mid $20/bbl area and if oil prices stay near current levels, the year over year price increase will be significant, nearly a doubling of the price of oil.


Saturday, August 20, 2016

Some Favorable Market Technicals But Awaiting A Resumption Of Earnings Growth

For the better part of a month the S&P 500 Index has traded in a very narrow range. Some strategists believe the market has come too far too fast since the June low and a correction is necessary before the market moves higher. We have noted from time to time that corrections can occur in price, i.e., a decline or in time, i.e., trade sideways for an extended period. At this point in time it appears the S&P 500 Index is attempting to go through a corrective phase by trading sideways over time. Of course, the length of time required to qualify for a correction over time is unknown. I believe one key determinant for this market is earnings over the course of the next four quarters which I will discuss later in this post.


One positive indicator on the above chart is the On Balance Volume indicator. The OBV measures volume on up days and volume on down days and accumulates the data over time. It is the trend of the OBV line that is important. If the line is trending up, trading volume is higher on up days versus down days and is an indication of buying demand. Up until this week equity fund and ETF flows were strongly negative. In Lipper's fund flow report earlier this week it is noted investors turned more favorable towards equities as equity flows turned positive with money market flows a negative $20.8 billion. The Money Flow Index (MFI) in the above chart is a volume weighted version of the Relative Strength Index (RSI). The MFI is not at a level indicative of an over bought market and similarly, the RSI is not at an over bought level either as can be seen in the below chart.


Friday, August 19, 2016

Highlights From S&P Dow Jones Indices Dividend Aristocrats Update

S&P Dow Jones Indices recently provided an update on the performance of the S&P 500 Dividend Aristocrats Index compared to the S&P 500 Index. It should be noted the Aristocrats index is an equally weighted index that is rebalanced quarterly. Index members are determined annually based on December year-end information with changes effective at the end of the subsequent January. I have written about the importance of dividends a number of times on this blog and this recent S&P update verifies the important role dividends play in an equity's total return. This post will provide some highlights from the S&P report and readers are encouraged to read the entire research paper.

Although dividends have accounted for a smaller percentage of the the total return for the S&P 500 Index over the past several decades, dividends remain an important component due to the favorable impact dividends have on compounding. As the below chart shows, since 1929 dividends have accounted for over one-third of the return of the S&P 500 Index.


Wednesday, August 17, 2016

Individual Investors Still Love Apple

From time to time I review the most active stocks by individual investors as compiled by Better Investing Magazine. I last updated the list in March and the two stocks that dropped off of the most active list from that time are Under Armor (UA) and Netflix (NFLX). The new additions are Wells Fargo (WFC) and Southwest Airlines (LUV). Apple (AAPL) has remained at the top of the list as far back as January 2015. Below is the most recent active list.


Tuesday, August 16, 2016

Should Investors Worry More About A Bond Or Stock Market Correction?

A great deal of commentary over the past few days has focused on the recent equity market trifecta, i.e., the Dow Jones Industrial Average, the S&P 500 Index and the Nasdaq Composite Index all hit new all time highs on the same day and the heightened potential for an equity market correction. Over the past week or so, LPL Financial Research has published some good analysis around the broad index participation in new highs and potential future market outcomes. Since 1980 12-month rolling returns have been positive 76.5% of the time. As the below table shows, when the Dow, S&P 500 and Nasdaq hit all time highs on the same day, the 12-month forward return is positive 75% of the time and averages 11.9%. I would recommend readers read the LPL article.


Thursday, August 11, 2016

History Suggests Record Equity Market Highs Do Not Mean Investors Should Sell Stocks

In late January and then in mid February I wrote posts noting our firm's positive view on the equity markets (here and here). It was a difficult position to take at the beginning of the year with the market in decline. As of the close today. and the first time since 1999, the S&P 500 Index, the Dow and the Nasdaq hit highs on the same day. Both the Dow and S&P 500 Index are up nearly 7% year to date. A number of high profile (often bearish though) investors/strategists are calling for a severe market correction. Knowing foresight is never perfect, should individual investors get out of equities now? History does not guarantee the future; however, the future tends to rhyme with the past.

LPL Financial Research published an interesting report today that addressed the question of, should an investor sell everything? Included in the report is a brief discussion on sentiment as well. A couple of worthwhile bullet points from the report:
  • There have been 40 other times the S&P 500 was up more than 6% for the year with 100 days to go (like 2016), and incredibly, the rest of the year is up 5.3% on average and higher 90% of the time.
  • Thus, a strong start to the year has led to even stronger returns for the rest of the year.
  • What about the full-year returns? Only once in history has the S&P 500 been up more than 6% with 100 days to go and finished red, and that was in 1929 (emphasis added).


The equity market will certainly experience some pullbacks; however, the positive economic data noted in earlier posts along with some not so bullish investor sentiment today, suggests this market seems to want to trend higher into year end.


Monday, August 08, 2016

Buyback Index Trails Broader S&P 500 Index

In an article earlier today I noted how corporate buybacks over the last two plus years have far outpaced U.S and foreign investors' outflow from equity investments. This strength in buybacks has not translated into outperformance for these buyback firms relative to the S&P 500 Index though. As the below chart shows, the cumulative total return performance of the Powershares Buyback Achievers ETF (PKW) has lagged the cumulative total return of the S&P 500 Index during the last two years. As background, the US BuyBack Achievers Index is comprised of US securities issued by corporations that have effected a net reduction in shares outstanding of 5% or more in the trailing 12 months.


The underperformance became more pronounced beginning in the fourth quarter of 2015. Comparing the two year results above with the one year returns shows the S&P 500 Index has returned 6.29% versus -.43% for PKW over the last 12-months. One headwind that has faced buyback focused investors is the yield differential on the buyback index versus say the iShares Select Dividend ETF (DVY). The yield on PKW is 1.4% and DVY has a yield of 3.0%. In this environment where investors prefer income, PKW's yield is even lower than the S&P 500 Index's yield of 2.1%. Historical stock buyback activity can be found at my post, Stock Buybacks Up Double Digits In First Quarter.


Most Everyone Is Bearish On Equities Except Companies

Last Friday the S&P 500 Index closed at its daily high of 2,182.87 and this equated to a 20.6% advance since the February 11th intra-day low. In spite of this strong advance from the February low and a price only return of 6.8% this year, most investors remain bearish on stocks.
  • This bearishness has translated into equity outflows of mutual funds and ETFs with bond investments capturing much of the inflows.
Source: ICI


Friday, August 05, 2016

Jobs Were The Missing Link?

The equity market's reaction to the above consensus job report today would make one believe the only missing link in the economic recovery was today's job's report. The 255,000 increase in nonfarm payrolls exceeded the consensus of 185,000 and the top range of 215,000. The end result is the S&P 500 Index was able to breakout of its sixteen day trading range.


Tuesday, August 02, 2016

Oil And Equity Price Trend Conundrum

A part of the anticipated improvement in forward earnings for the S&P 500 Index is an improvement in the energy sector. The health in the energy sector has spillover into other sectors of the market like the industrial sector that sells into the energy space. Of late, however, oil prices have pulled back significantly from over $50/bbl in June and dropping below $40/bbl yesterday. This decline in price can be directly attributable to the elevated supply of crude.


Saturday, July 30, 2016

Income Oriented Equities Lag In July

In a few recent posts I have discussed the elevated valuation of dividend growth equities. It would appear bond investors have gravitated to the anticipated safety of equities that generate dividend income greater than can be found in the low rate bond market. The extended valuation of these income equities/sectors may result in investors being surprised in the event the market does encounter a pullback. In fact, August and September tend to be the the poorer performing months for stocks.

Just as the "sell in May' mantra has yet to play out this year, maybe the much anticipated August/September weakness becomes more discussion than reality. And given all the concern about this late summer weakness, in July, investors seemed to rotate out of the so-called safe income stocks and into the higher beta, more cyclical equities. As the below chart shows, the income oriented equity market segments underperformed the broader S&P 500 Index and the PowerShares S&P 500 High Beta ETF (SPHB).


From a sector perspective, the more defensive sectors in the S&P 500 Index lagged the more cyclically oriented ones as well. Energy has its own issues and the other bottom three performing sectors in July were Consume Staples, Utilities and Telecommunications. On a year to date basis the performance of these three sectors remains strong; however, Technology, Materials, Health Care and Industrials generated strong returns in the month of July. An important factor for continued strong performance in the cyclically oriented sectors is improved earnings.

 
In Thomson Reuters This Week in Earnings report, they note,
"312 companies in the S&P 500 Index have reported earnings for Q2 2016. Of these companies, 72% reported earnings above analyst expectations, 12% reported earnings in line with analyst expectations and 16% reported earnings below analyst expectations. In a typical quarter (since 1994), 63% of companies beat estimates, 16% match and 21% miss estimates. Over the past four quarters, 70% of companies beat the estimates, 9% matched and 21% missed estimates. In aggregate, companies are reporting earnings that are 4% above estimates, which is above the 3% long term (since 1994) average surprise factor, and in line with the 4% surprise factor recorded over the past four quarters."
Absent the energy sector, overall earnings appear to be on an improving trend. With respect to the energy sector, year over year comparisons will become easier starting with the third quarter.

Given the tight range the S&P 500 Index has traded in over the last two weeks, a break to the upside or downside will certainly occur. Historically, these tight trading ranges tend to resolve themselves to the upside. Having noted this, a little consolidation of the market gains since February would be healthy and not a surprise given the upcoming weak seasonal market months. And finally, investors chasing yield in stocks need to be cognizant of the rich valuations of these stocks and recent rotation may indicate some investors are figuring this out.


Thursday, July 28, 2016

Sentiment: Bullish Institutions Versus Bearish Individuals

This week's NAAIM Exposure Index was reported at 101, only the fifth time the exposure index has been reported above 100 since the index's inception on July 5, 2006. The NAAIM Exposure Index consists of a weekly survey of NAAIM member firms who are active money managers and provide a number which represents their overall equity exposure at the market close on a specific day of the week, currently Wednesday. Responses are tallied and averaged to provide the average long (or short) position or all NAAIM managers as a group.


Conversely, today individual investor bullish sentiment, reported by the American Association of Individual Investors, fell four percentage points to 31.3%. This is below the long term average of the bullish sentiment reading of 38.5%.


The individual investor sentiment measure is considered a contrarian one as individual investors tend to be the most bullish near market tops and the least bullish near market bottoms. So, if this is the case, and institutions tend to be on the bullish or right side of the allocation debate, are these two readings indicating the market has more room to move to the upside?

Below is a table comparing the prior NAAIM readings above 100, the AAII individual bullish sentiment reading and the subsequent one year return for the S&P 500 Index. Although the number of NAAIM readings is small, the subsequent 12-month return for the S&P 500 Index has averaged a low double digit positive return when NAAIM readings were above 100.


Lastly, the S&P 500 Index has traded within a very tight 1% trading range for the last eleven trading days. From a positive standpoint, markets can correct in price (a steep decline), or over time. This sideways trading range may be one where a correction is occurring over time. The obvious questions is whether the market breaks to the upside or to the downside.


Additional commentary, and an interesting one, highlighted by Ryan Detrick, CMT of LPL Financial, on the market level and whether or not it is in a bubble can be read in an research report, Is the S&P 500 in a Bubble?.


Friday, July 22, 2016

Weak Investor Sentiment Yet New Equity Market Highs

Today the S&P 500 Index closed at another all time record high. This higher advance in the market is becoming a regular occurrence as this is the fourth consecutive week for the market to close higher on a weekly basis. From the market's intraday low on February 11th, the S&P has advanced over 20% on a price only basis.


The magnitude and trajectory of the move higher is seen more clearly on the daily chart below.


Somewhat interesting is the fact individual investor bullish sentiment as reported by the American Association of Individual Investors is far from indicating excess optimism. This week's bullishness reading of 35.43% was a decline from the prior week's reading of 36.87%.  The long term average bullishness level is 38.5% and bullish sentiment has not exceeded this level since early November of last year.


So given the strength of this move in the market since February, and reviewing some of the technical market indicators, a pullback would not be surprising. However, in a June 2nd article I posted, Is It Right To Be Bullish Near A Record Market High?, I noted:
"Being bullish after a double digit market decline seems a lot easier than being bullish near market tops. Knowing the market does not move up or down in a straight line, are there factors we see that would support higher equity prices? In the intermediate and long run, we believe fundamental company and economic factors are key drivers of stock price returns."
Our view that company and economic data will continue to remain favorable is unchanged from early June.

Lastly, Ryan Detrick, a strategist at LPL Financial, provided a link to one of his firm's recent research reports, Is an Overbought Condition Necessarily Bad for the Stock Market?. This research article is a worthwhile read for investors. The conclusion might surprise some readers. In the end, the market will not move higher in a straight line; however, this longer term trend seems to be a friendly one for investors at the moment.


Wednesday, July 20, 2016

Summer 2016 Investor Letter: Searching For Yield

In our just published Summer 2016 Investor Letter, we explore the investor's pursuit of income generating investments. In our view this has led to extended valuations in some of the income yield segments of the equity market, for example, utility stocks. If interest rates do remain lower for longer then the extended valuations in the income yielding sectors could remain elevated. The Investor Letter contains broader commentary on this topic.

Our last newsletter mentioned the potential issues surrounding the U.K.'s potential withdraw from the European Union (Brexit). Just a few weeks ago the voters in the U.K. spoke at the ballot box and voted to leave the EU. We wrote separate commentary on Brexit in the days following the vote; however, we include additional highlights in the Summer 2016 Investor Letter on the Brexit topic and more.


For additional insight into our views for the market and economy, see our Investor Letter accessible at the below link.


A Look At Projected Sales And Earnings Growth

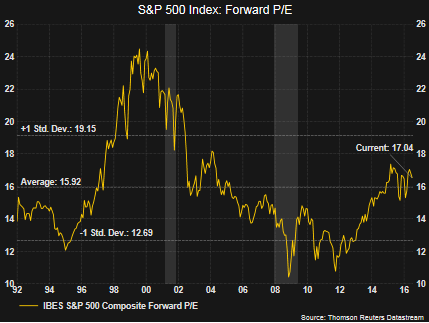
In spite of the S&P 500 Index trading sideways for most of the last 18 months until very recently, the advance from the financial crisis low has been strong. A part of the return generated from equities has been the fact the forward P/E multiple has expanded from low double digits to just over 17 times earnings.


In a low interest rate environment stocks tend to trade at higher P/E multiples. The current forward multiple on the S&P 500 Index is certainly not low; however, the current forward P/E level is not giving off a signal of overvaluation either. Importantly, going forward, we believe growth in stocks will need to be driven by growth in earnings since a large part of the return from multiple expansion is behind us.

Not only is earnings growth obviously important, company revenues need to see growth as well. As the below chart shows, expectations are pointing to stronger earnings growth as one looks one year into the future and top line sales are expected to grow as well. We believe the equity market's strong recovery from the February low earlier this year is partly due to the improved outlook for corporate earnings and revenue growth. The equity markets seem to be anticipating this better environment.


In a post written a few days ago, Value Stock Outperformance May Indicate Stronger Economy Ahead, I highlighted the fact analysts are projecting Q2 2017 (one year forward) earnings growth of 15.3% for the S&P 500. Equally important, the top line is anticipated to return to growth as well.

Lastly, the market recently broke out of its 18-month trading range on a near parabolic move to the upside. It would be nice, and expected, to see the market consolidate some of these gains, but positively, selling volume does not seem to be taking hold.


Sunday, July 17, 2016

Value Stock Outperformance May Indicate Stronger Economy Ahead

Over the course of the past few years several times I have touched on the significance of the value versus growth stock performance cycle. A couple of the earlier articles contain useful information for investors that provides insight into the economic cycle being telegraphed by the value/growth cycle. In short, in a slowing economic environment, growth tends to outperform value and the opposite tends to occur when the economy is strengthening. Value has been outperforming growth this year.


In the March 2014 article, Why It Matters That Value Stocks Are Outperforming Growth Stocks, value's outperformance peaked around April of that year and growth went on a nearly two year run of beating value. The backdrop for this reversal from value to growth is provided in the just noted article, but economic data began to rollover. In an article early this year, Is The Value Style Outperformance Sustainable?, detail is provided on the trend reversal in 2014 from value back to growth as well as value's strength now.

Fast forward to today and the iShare equivalent of the S&P 500 Value Index is outperforming the S&P 500 Growth Index, 9.21% versus 4.79%, respectively. A significant factor contributing to value's strength is the investor focus on income producing equities in a world where bond rates are low, near zero and in some cases below zero. The below graphic compares the sector weights of the S&P 500 Value and Growth indices. The two top performing sectors this year are telecoms, up 24% and utilities, up 22%. Combining these two sectors, telecoms plus utilities, they have a weighting of 11.2% in the value index and only 1.3% in the growth index. Additionally, in each of the six top performing sectors, value's sector weighting is greater than in growth's.


Positively, the next three best performing sectors, energy, materials and industrials, tend to be economically sensitive ones. And, if one believes the equity market serves a bit like a weighing machine, the better performance in these three sectors may just be anticipating a better economic environment ahead.

Friday's industrial production report for June of .6% was better than the high end consensus expectation. The report contained many positives signalling an improving manufacturing sector, retail sales exceeded expectations (.6% vs .1% consensus) and jobless claims of 254,000 were lower than the 265,000 consensus.


With earnings projected to improve as one looks one year forward and economic activity just maybe swinging more positive, there remains the possibility that value's outperformance might last more than just a few quarters this time around. The one concern is the overvaluation of some of the income yielding sectors like utilities; however, investors may still find attractive values in the the more economically sensitive sectors.


Saturday, July 16, 2016

Market Breaks From Trading Range While Sentiment Measures Remain Mixed

The S&P 500 Index has recovered all that was lost in the two day selloff following the Brexit vote. Since the Brexit low, the S&P 500 Index is up over 8.5% and this has taken the index out of its 18+ month trading range. As the below chart shows, the trading range goes back to the end of 2014 and up until this week, the only breakout from the range had been to the downside.


Saturday, July 09, 2016

Dividend Payers And Dividend Focused ETFs Post Strong Returns YTD

A few prior posts have provided detail and potential consequences facing dividend focused equities given their extended valuations. Of course, in a low (and going lower?) interest rate world it seems the simple approach an investor can pursue is just buying a stock that has a higher yield than the 10-year U.S. Treasury. S&P Dow Jones Indices recently reported on the average performance of the dividend and non dividend paying stocks in the S&P 500 Index. Maybe no surprise, but the payers are swamping the non payers this year and over the last twelve months as of June 30, 2016. As the below table details, the payers have outperformed the non payers by 728 basis points year to date and by 1,142 basis points over the prior twelve months.


Also, the strong performance of the dividend payers is evident in several of the dividend focused ETFs. Below is a chart of the SPDR S&P Dividend ETF (SDY) and the iShares Select Dividend ETF (DVY) plotted with the S&P 500 Index.
  • SDY seeks to replicate the performance of the S&P High Yield Dividend Aristocrats. SDY's projected income yield is 2.3%. Notable sector weights in SDY are Utilities (31%) and Financials 14%.
  • DVY's performance is focused on replicating the Dow Jones Select Dividend Index and has a projected yield of 3.0%. Notable sector weights for DVY are Financials at 24% and Utilities at 15%.
Both of these ETFs are up by mid teen percentages this year through Friday's close as can be seen in the below chart.


A Look At The PEG Ratio: Earnings Growth Versus Valuation

In an article I wrote about a week ago, I reviewed the current P/E (price earnings ratio) of the sectors that comprise the S&P 500 Index. The article included the below chart which compared the current sector P/Es to the respective sector's average P/E and minimum P/E over the past ten years. the article noted some of the income or yield producing sectors were trading at elevated valuations.


Simply because the P/E for a sector is high, and the same applies to individual stocks, this does not necessarily mean the sector or stock is overvalued. Importantly, the P/E should be compared to the earnings growth rate for each sector or company. By dividing the P/E by the earnings growth rate, one obtains the PEG ratio (PE to growth rate.) A good discussion on this is contained in an article on the CFA Institute's Inside Investing blog, Is It Overvalued? Look at the PEG Ratio. When evaluating the PEG, a PEG of 1.0 is an indication a sector or company is fairly valued. If the PEG is less than 1.0, this is an indication the sector or company may be undervalued. Conversely, PEGs greater than 1.0 are indications of overvaluation relative to fair value.

As can be seen in the above chart, the energy sector is trading at a P/E of greater than 40, but what is the PEG? Below is a chart comparing the sector P/Es to each sector's PEG ratio. The growth rate used in the denominator is Thomson Reuters' I/B/E/S earnings growth rate for Q2 2017, or one year forward.


Below is the table detailing the earnings growth rates for each sector as reported in Thomson Reuters' 7/8/2016 This Week In Earnings report.


Clearly, the PEG for the utility sector shows investors that are buying utility stocks are paying up for the single digit earnings growth. As discussed in last week's post, one reason this has occurred is investors are purchasing dividend yielding investments in part because they are unable to get that yield in bonds. This reach for yield appears to have pushed some of these yielding sectors and stocks to elevated valuation levels. The first chart in this article does show the forward P/E for utilities is higher than the 10-year average P/E for the sector as well.

The other factor to note is some stocks/sectors trade at higher PEs. Looking at the telecommunications sector for example, the current forward P/E is lower than the sectors 10-year average P/E. As a result, comparing each individual sector's P/E and earnings growth rate with its respective historical data is also important.

And finally, P/E and earnings growth rates are only a couple of factors investors should use in evaluating equity investment opportunities; however, the PEG ratio can be useful as a starting point. In the end, just because a company appears to be great, does not mean it is a great investment at all points in time. Recently, investors have pursued income yielding investments for their safety characteristics. However, many of these income investments are priced, as we call 'for perfection'. In other words, the slightest bit of negative news for some of these yield plays could result in strong price declines.

Sunday, July 03, 2016

An In Depth Look At The Extended Valuation Of Defensive And Income Yielding Equity Sectors

Early last week I highlighted the extended valuation of the utility sector in part due to investor demand for income yielding stocks. Not only are the income sectors attracting investor dollars, defensive sectors like consumer staples are as well. A result of this investor demand for defensive and income producing equities is these sectors have produced market beating returns so far in 2016. As the below sector return chart shows, the defensive consumer staples sector and the income yielding sectors like utilities and telecommunications have generated strong returns this year.


However, the strong return in these sectors has pushed the sector valuation beyond the average longer term valuation for each respective sector itself. The better performing sectors, utilities and staples are some of the most extended compared to the other sectors. Energy sector valuations are at extremes, largely due to earnings headwinds resulting from lower oil prices.


Saturday, July 02, 2016

The Pursuit Of Yield Continues To Benefit Return For 2016 Dogs Of The Dow

Investors' continued pursuit of income in this low bond interest rate environment has led them to higher yielding stocks. Partial evidence of this can be found in the total return of the Dogs of the Dow basket of stocks this year. As noted in earlier posts, the Dogs of the Dow strategy is one where investors select the ten stocks that have the highest dividend yield from the stocks in the Dow Jones Industrial Index (DJIA) after the close of business on the last trading day of the year. Once the ten stocks are determined, an investor invests an equal dollar amount in each of the ten stocks and holds them for the entire next year.
The average YTD total return through July 1, 2016 of the ten 2016 Dogs of the Dow equals 15.4%. This compares to the Dow SPDR and S&P 500 SPDR returns of 4.4% and 4.0%, respectively. The top performing Dow Dog this year is Verizon (VZ), returning 24.5%. Of course, it was also the highest yielding Dow Dog at the beginning of 2016. Below is a table containing various metrics on the 2016 Dogs of the Dow.


A full list of the Dow stocks with return and yield data can be found at the Dogs of the Dow website.