Saturday, April 24, 2010

More Companies That Increased Dividends Last Week

Catching up on some dividend announcements from this past week: Johnson & Johnson (JNJ), Southern Company (SO), Kellogg (K).


Johnson & Johnson
  • announced a 10.2% increase in the quarterly dividend to 54 cents per share versus 49 cents per share in the same quarter last year.
  • based on 2010 estimated earnings per share of $4.85, the projected payout ratio is 45%. This compares to the 5-year average payout ratio of 41%.
  • JNJ carries an S&P Earnings & Dividend Quality Ranking of A+.

Southern Company
  • announced a 4% increase in the quarterly dividend to 45.5 cents per share versus 43.75 cents per share in the same quarter last year.
  • based on 2010 estimated earnings per share of $2.35, the projected payout ratio is 77%. This compares to the 5-year average payout ratio of 74%.
  • SO carries an S&P Earnings & Dividend Quality Ranking of A-.

Kellogg
  • announced a 8% increase in the quarterly dividend to 40.5 cents per share versus 37.5 cents per share in the same quarter last year.
  • based on 2010 estimated earnings per share of $3.59, the projected payout ratio is 45%. This compares to the 5-year average payout ratio of 47%.
  • K carries an S&P Earnings & Dividend Quality Ranking of A+.


Disclosure: Long interest in JNJ, K


Thursday, April 22, 2010

Investor Sentiment Volatility

This week's investor sentiment survey reported by the American Association of Individual Investors saw a decline in bullish investor sentiment of over 10 percentage points. The bullish sentiment reading was reported at 38.12% versus the prior week's reading of 48.48%. Eleven out of the first sixteen weeks of this year saw changes in the sentiment reading of + or - five or more percentage points. This is a similar number of weeks as were reported in the first four months of 2009. The 8-period moving average of the bullishness reading increased to 40% versus last week's level of 39.6%. This is the fourth consecutive week that the 8-period moving average has increased. The bull/bear spread narrowed to 4% versus 19% last week.


Tuesday, April 20, 2010

Procter & Gamble Increases Dividend 9.5%

For the 54th consecutive year, Procter & Gamble (PG) announced it is increasing the company's quarterly dividend. The new quarterly dividend increases 9.5% to 48.18 cents per share versus 44 cents per share in the same period last year. The estimated payout ratio will equal 48% based on June 2011 estimated earnings of $4.05. The 5-year average payout totals approximately 42%. P&G carries an A+ S&P Earnings and Dividend Quality Ranking.


Disclosure: long interest in PG


Sunday, April 18, 2010

Magnitude Of Rally Not In Uncharted Territory

An interesting chart published by Chart of the Day compares the current post bear market rally to similar periods that occurred in the past.


As Chart of the Day states,
"a 'massive' bear market is defined as a decline of greater than 50%. Since the Dow's inception in 1896, there have been only three bear markets whereby the Dow declined more than 50% (early 1930s, late 1930s until early 1940s, and during the very recent financial crisis). Today's chart also adds the rally that followed the dot-com bust during which the Nasdaq declined 78%. One point of interest is that the current Dow rally has followed a path that is fairly similar to that of the Nasdaq rally that began in late 2002. It is also worth noting that each rally lasted from about 300 to 370 trading days and then moved into a trading range/choppy phase that lasted for a year or more. In the end, the current post-massive bear market rally is by no means atypical."
So are we entering a range bound or choppy phase in the market? Seasonal influences could impact upcoming trading as the summer months approach.


Stock Buybacks: Actions Speak Louder Than Words

Companies in the S&P 500 Index are once again announcing stock buybacks with an increase in buybacks in the fourth quarter last year. Standard & Poor's reports though, the buybacks are essentially offsetting dilution from employee's exercising stock options. S&P reports that most of the companies that had actual reductions in share count in the 4th quarter were found in the consumer discretionary sector.

In looking at the actual dollars expended on buybacks:
  • $47.8 billion in Q4, 2009, $34.8 billion in Q3, 2009 and $24.2 billion in the record setting low period of Q2, 2009.
  • The high point for buybacks occurred in Q3, 2007 when $172 billion of stock were repurchased by companies.
Source: BusinessWeek

As the above chart notes buybacks are on the increase (red line). A true factor worth watching is a substantial increase in dividends paid. The fourth quarter saw a small increase in dividends paid out over Q3, 2009, $49.04 billion versus $47.21 billion, respectively. Dividend payments are a longer term commitment by companies and signal stronger business prospects than buyback announcements. As the below chart notes, cash is accumulating on corporate balance sheets. Commiting to a growing dividend payment would be a positive sign.


Bullish Investor Sentiment Continues Moving Higher

This past week's investor sentiment survey that was released by the American Association of Individual Investors indicates individual investors continue indicating they are more bullish. This past week's bullishness reading was the fourth straight week that the reading came in at a higher level than the prior week. Additionally, the 8-period moving average increased for the fourth straight week as well.

The individual investor bullishness reading was reported at 48.48% versus last week's reading of 42.86%. The 48%+ reading is the highest level reached this year. After Friday's market action and the Goldman Sachs (GS) news, next week's reading may see a dip.


Friday, April 16, 2010

Household Survey Versus Non Farm Payrolls

Which payroll survey is more accurate: the Nonfarm Payroll (Establishment) survey, which shows 162,000 new jobs have been created since December or the Household survey, which shows over 1 million new jobs have been created since December?


Argus Research notes:
"In the year ending August 2003, for example, the Payroll survey originally showed a loss of 463,000 jobs, whereas the Household Survey showed the economy had added 313,000 jobs. At that time, Carnegie Mellon economist Alan Meltzer wrote that the reason for the discrepancy is 'that the number of companies does not remain fixed. In our dynamic economy, old firms die and new ones are born. The Labor Department learns about the deaths quickly, but it takes longer to learn about the births.'"

"In periods of significant downsizing, such as the past two recessions, we think the Household survey is much more likely to be accurate. Using available surveys, we calculate that since 1948, the bottom in Household employment has, on average, occurred 2.9-months before the bottom in Payroll employment. We conclude that U.S. employment bottomed in December."


Saturday, April 10, 2010

Investors Continue Piling Into Bond Funds

One thing investors have a tendency to do is chase returns. Market technicians look at investor fund flow data as a contrarian signal. Given the poor long term return of many stock related investments and the strong bond returns one would think investors might be more attracted to equity investments at the moment. In fact bonds have outperformed stocks over the last 10 and 20 year period and given the low level of interest rates can this possibly continue? In a recent research piece by Fidelity titled, Stocks Anyone? (PDF), it is noted,
"investors actually took money out of stock funds on a net basis during the past year. Meanwhile, the $385 billion of net flows investors put instead into bond funds is more than they ever put into stock funds during a 12-month period—even during the technology bubble of the late 1990s."
Although investors are investing some of their funds into equities, a majority of the inflows are going into bond funds as outlined in the below table.


Additionally, the below charts indicate graphically that investors do have a tendency to chase returns; however, that has not been the case over the course of this past year. Although stocks are outperforming bonds significantly, net flows continue to favor bond funds.


Maybe the significant equity shocks of the last decade (technology bubble and real estate bubble) have resulted in investors taking a longer perspective on equity returns. The below chart compares the 10-year rolling relative performance to fund flows.


This lack of investor interest in stocks is a contrarian sign that suggest equity investors might have a performance advantage compared to bond investors on a forward looking basis.

Source:

Stocks Anyone? (PDF)
Market Analysis, Research & Education
Fidelity
By: Dirk Hofschire, CFA
March 25, 2010
http://personal.fidelity.com/products/pdf/stocks-anyone.pdf


Thursday, April 08, 2010

TJX Cos. Increases Dividend 25%

Earlier this week TJX Cos., Inc (TJX) announced a 25% increase in the company's second quarter dividend. The new quarterly dividend will be 15 cents per share versus 12 cents per share in the same period last year. The dividend payout ratio is projected to equal 19% based on estimated January 2011 earnings of $3.18. The projected payout compares to the 5-year average payout ratio of 16%. TJX carries an S&P Earnings & Dividend Quality Ranking of A+.


Bullish Investor Sentiment Essentially Unchanged

This week's sentiment survey reported by the American Association of Individual Investors saw a small uptick in bullish investor sentiment. The bullishness reading came in at 42.86% versus 41.30% last week. The 8-period moving average has moved higher for the third straight week., increasing to 38% versus 37.2% last week. The AAII survey represents the percentage of individual investors who are bullish, bearish, and neutral on the stock market for the next six months; individuals are polled from the ranks of the AAII membership on a weekly basis.


The Key Is Cash Flow

A recent article appeared in Forbes magazine that focused on the importance of cash flow versus earnings per share. The article, Investing Via Cash Flow, highlighted the success of Martin Saas, chairman of MD Saas. In the Forbes article, Saas notes, "investors get too fixated on the reported earnings...I am religious about cash flow. To me it's the most important number." Saas believes investors should start their review of the financial statement with the "cash flow from operations" statement.
This essentially consists of net income with noncash charges (like depreciation and deferred taxes) added back and cash-draining events (like an inventory pile-up) taken out. Now subtract maintenance-level capital expenditures. The company will tell you its total cap-ex; divining how that divides between maintenance and expansion is a tricky business, but you can strip out discretionary expenditures such as when oil companies increase drilling activity. What you're left with is free cash flow.
Source:

Investing Via Cash Flow
Forbes Magazine
By: Daniel Fisher
March 25, 2010
http://www.forbes.com/forbes/2010/0412/investing-cash-flow-sass-equities-ebitda-cash-does-not-lie.html


Sunday, April 04, 2010

The Impact Of Higher Taxes On Stock Prices

In an effort to look past the health care rhetoric, one aspect of the legislation that we know is coming is higher tax rates. In addition to the higher taxes that are a apart of the new legislation, the Bush tax cuts will expire after 2010 as well. So what does history say about higher taxes and stock prices.

It has been 23 years since capital gains tax rates were increased. The last increase occurred when Ronald Reagan was president. A big part of what Reagan did with taxes was lower the highest marginal tax rate on income from 50% to 28%. However, Reagan did increase the tax rate on capital gains from 20% to 28% beginning in January 1987. What occurred in 1986 was the unleashing of the corporate raider. A recent article in Financial Advisor magazine noted:
It was the age of the corporate raider and folks like T. Boone Pickens. Carl Icahn and Ronald Perelman were making the CEOs of America's biggest companies quake in their stretch limos. With a huge assist from Drexel Burnham Lambert's junk bond department in Beverly Hills, these characters were putting companies into play on a weekly basis. The rest of Wall Street was frantically scrambling to clone Drexel's incredible profit machine and struggling to create their junk bond units to finance LBOs....

When the 1986 tax act became law, these raiders sensed opportunity and took off on a bender that would last for more than two years. Shareholder value was their mantra. Almost every day, they would tee up companies and demand that their boards work over time to quickly complete the deal to give shareholders the full advantage of the soon-to-expire 20% capital gains tax rate. In actuality, most raiders were hoping that a bigger corporation, or so-called white knight, would swoop in and trump their offers.

Did the expiration of the 20% capital gains tax rate in January 1987 hurt stock prices? Hardly. From January to September, equities went crazy. Propelled perhaps by the big cut in income tax rates, the Dow climbed from 1,897 to over 2,700 on August 25 in a frenzy that looked like a runaway train going down Mt. Everest.
The fall out from this junk bond era is well know, but it is worth noting that stocks performed well during this time period. For bond holders, they should have some knowledge of history.
Fed chairman Paul Volcker discerned the all-too-obvious symptoms of an overheating economy and decided he'd had enough of all this nonsense. In April, he jacked up interest rates dramatically, triggering a $100 billion bath for bondholders around the globe.
One aspect that is different this time is income taxes will be on the rise. David Kelly, chief market strategist for J.P. Morgan Funds notes:
  • starting in 2013, the Medicare tax rate on households with income over $250,000 will be increased from 1.45% to 2.35%.
  • a new 3.8% Medicare tax will be introduced for this same group on investment income.
  • the tax rate on dividends and long-term capital gains will increase from 15% to 20% for households earning over $250,000 and with the new Medicare tax, these rates will rise to 23.8% for the same group.
  • Under current tax law, investors get to keep 85% of the income stream from taxable stock market investments. Under this new law this will be cut by 8.8% to 76.2%, reducing the value of the income stream by 10.4% (that is 8.8% of 85%).
  • using a number of broad assumptions, the value of the average stock should be reduced by one quarter of 10.4% or 2.6%—not good obviously, but also not an overwhelming reason to avoid stocks after a 12 month period in which they rose by over 70% and still appear undervalued.
Certainly, an investor's income stream will be impacted by the higher tax rates. The question becomes what are the alternatives to stocks and dividend paying stocks for that matter? If the Fed is preparing to raise interest rates (maybe not until later this year), what will be the impact on bonds? Additionally, with the precarious budget situation with a number of municipalities, tax free bonds may not be the safe haven expected by many investors. In short, don't let the tax tail wag the dog. Some perspective on history is contained in the article, Animal Spirits: The Last Time Capital Gains Taxes Rose.

Source:

Animal Spirits: The Last Time Capital Gains Taxes Rose
Financial Advisor Magazine
By: Evan Simonoff
March 25, 2010
http://www.fa-mag.com/blog/evan-simonoff/5357-animal-spirits-the-last-time-capital-gains-taxes-rose.html

Investment Implications of Health Care Reform
Financial Advisor Magazine
By: David Kelly, chief market strategist for J.P. Morgan Funds
March 22, 2010
http://www.fa-mag.com/online-extras/5344-investment-implications-of-health-care-reform.html


Dividends And Buybacks On The Increase

It is projected that dividends and stock buyback activity will increase in the second quarter of 2010 versus 2Q 2009. According to Howard Silverblatt, Senior Index Analyst at Standard & Poor's:

[expectations are that] second quarter 2010 dividend payments will be higher than second quarter 2009, but still 17% off 2Q 2008. A surge in increases is expected late in the third quarter if companies feel secure in their prospects to commit to future payments. 2010 payments are estimated to be up 5.6% to US$206B. This compares to payments of US$196B in 2009, US$248B in 2008, US$247B in 2007, and US$ 225B in 2006.

With respect to buybacks, Howard Silverblatt notes:
[buybacks are estimated to show] a 37% increase in fourth quarter 2009 over the third quarter 2009, which is 1% less than the fourth quarter of 2008 and 66% less than 4Q 2007. Looking at issues, MSFT (US$ 3.87B versus US$ 1.54B for Q3 2009), KO (US$ 1.51B versus minor) and PG (US$ 1.46B versus US$ 0.01B) returned, with HPQ increasing (US$ 2.7B versus US$ 2.1B), as CSCO (US$ 1.37B versus US$ 1.87B) and DTV (US$ 0.08B versus US$ 0.94B) reduced.

Overall, dollar purchases are ahead by over 39%, but are up 30% void of top issues. Lots of buyback announcements have occurred, but they come down to authorizations and a willingness to get back in the market – actual buys will depend on market conditions. Given that companies are still covering options to prevent dilution...

Source: Standard & Poor's


Friday, April 02, 2010

For Dividend Investors, It Is All About The Cash

As important as the stock yield percentage might be for investors, looking at dividend growth investments is more than simply looking at the yield on a particular stock. Certainly, history shows that a large part of the market's total return is attributable to the dividend return. Since 1926 the dividend component of the S&P 500 has accounted for one-third of the index's total return. An important aspect of focusing on dividends is it provides an investor insight into a company's cash flow.

One of the most important financial statements an investor can review when evaluating a company is the cash flow statement. A recent article reacquaints investors with the importance of this statement. One thing a company can't manipulate is cash. Cash is cash and cash is king as they often say.

As the article, Show Me the Money: Tracing a Firm's Cash Flow, shows, the cash flow statement provides investors with a wealth of information. Under the "financing section" of the statement, investors should pay particular attention to the activity surrounding the stock account. Many companies are once again announcing stock buybacks, but are the buybacks actually reducing the shares that are outstanding? Maybe the buybacks are simply offsetting potential dilution from option exercises.

The Show Me The Money article is timely for investors as many companies are once again focusing on dividends and buybacks as company fortunes seem to have stabilized.


Thursday, April 01, 2010

Dividend Payers Outperform Non Payers In First Quarter Of 2010

During the first quarter of 2010, the dividend payers in the S&P 500 Index outperformed the non dividend paying issues. The outperformance was small with the payers average return equaling 8.37% versus 8.35% for the non payers. In the month of March, no S&P 500 company reduced or suspended its dividend. This compares to March 2009 when 12 companies reduced their dividends.

What is interesting to note about the quarterly performance results is the dividend payers only outperforming month was January when the the payers were down 2.5% and the non payers were down 4.8%. Losing less money in down markets is one key to achieving longer term performance goals. Dividend payers are one way to take advantage of this performance advantage.


Uptick In Bullish Investor Sentiment

This week's individual investor sentiment as reported by the American Association of Individual Investors saw an uptick in bullish sentiment. The bullish sentiment reading increased 8.9 percentage points to 41.3%. This is slightly above the long term average of 39%. Additionally, the less volatile 8-period moving average of the bullish sentiment reading increased to 37.2% versus last week's average of 35.7%. This is the first increase in the 8-period average since January 14th.


Sunday, March 28, 2010

Misconception Surrounding The Importance Of The Asset Allocation Decision

Many investment advisers will indicate that one of the most important variables an investor needs to determine is their asset allocation. The reason behind this has to do with a study completed over 20 years ago by Brinson, Hood and Beebower that indicated that 93.6% of an investor's return is attributable to asset allocation. I wrote a post on this study a few years ago titled, Asset Allocation: Pros and Cons.

In a study reported in the March/April 2010 Financial Analyst Journal titled, The Equal Importance of Asset Allocation and Active Management and written by James Xiong, CFA, Roger Ibbotson, Thomas Idzorek, CFA and Peng Chen, CFA, it is shown that asset allocation is not nearly as important as many believe. In another article in the March/April 2010 FAJ, The Importance of Asset Allocation (PDF), Roger Ibbotson provides a summary of the aforementioned study.

In the summary several important conclusions are noted:
  • many investors mistakenly believe that the BHB (1986) result (that asset allocation policy explains more than 90 percent of performance) applies to the return level (the 100 percent answer). BHB, however, wrote only about the variation of returns, so they likely never encouraged this misrepresentation.
  • In general (after controlling for interaction effects), about three-quarters of a typical fund’s variation in time-series returns comes from general market movement, with the remaining portion split roughly evenly between the specific asset allocation and active management.
  • Do the BHB (1986) time series have any meaning at all in explaining the incremental importance of a specific asset allocation policy? Not necessarily. Perhaps the simplest illustration was given by Mark Kritzman (2006) in a letter to the editor of this journal titled “‘Determinants of Portfolio Performance—20 Years Later’: A Comment.” Kritzman constructed an example in which stock and bond returns moved up and down perfectly together (i.e., were equal to each other each year) while underlying securities did not. The BHB methodology incorrectly ascribed all 100 percent of the return variation to asset allocation, whereas, in fact, all the variation came from stock selection and general market movement.
  • The time has come for folklore to be replaced with reality. Asset allocation is very important, but nowhere near 90 percent of the variation in returns is caused by the specific asset allocation mix. Instead, most time-series variation comes from general market movement, and Xiong, Ibbotson, Idzorek, and Chen (2010) showed that active management has about the same impact on performance as a fund’s specific asset allocation policy (emphasis added).
Investors are encouraged to read the Ibbotson summary to get a clearer perspective on asset allocation decisions.


Thursday, March 25, 2010

Bullish Investor Sentiment Continues To Deteriorate

The market continues to advance in spite of continued weakness in the bullish investor sentiment reading from the American Association of Individual Investors. The weekly readings can be somewhat volatile, but looking at the 8-period moving average can smooth out this volatility. The 8-period M.A. of the bullishness reading has declined for ten straight weeks going back to January 14, 2010. Since this is a contrarian indicator, it will be interesting to see how this plays out over the course of the next quarter.


Data Source: AAII.com


Friday, March 19, 2010

Dow Rally Below Average In Duration & Magnitude

The Chart of the Day has an interesting chart this week that shows the current Dow Jones Industrial Average rally compared to past rallies back to 1900. It may come as a surprise to many investors, but this rally is below average in duration and below average in magnitude of the advance. The Chart of the Day notes:
  • each dot on the chart represents a major stock market rally as measured by the Dow
  • as the chart illustrates, the Dow has begun a major rally 27 times over the past 110 years which equates to an average of one rally every four years.
  • most major rallies (73%) resulted in a gain of between 30% and 150% and lasted between 200 and 800 trading days -- highlighted in the below chart with a light blue shaded box.


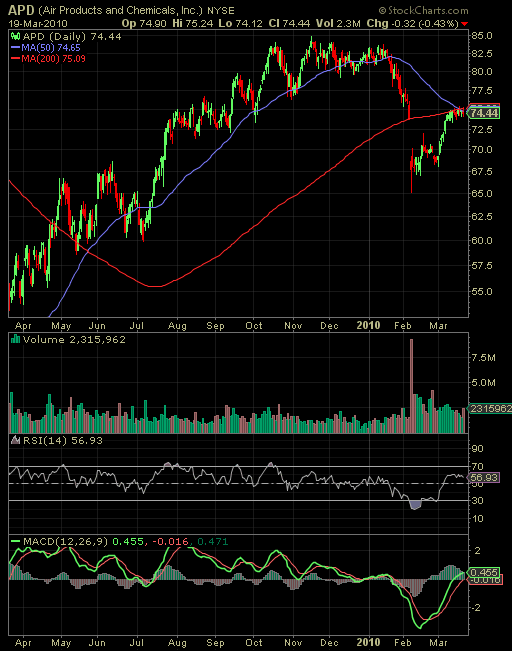
Air Products Increases Dividend 9%

On Thursday Air Products & Chemicals (APD) announced a nearly 9% increase in the company's second quarter dividend. The new quarterly dividend increases to 49 cents per share versus 45 cents per share in the same quarter last year. The payout ratio is estimated at 40% based on September 2010 EPS estimates of $4.92. The 5-year average payout ratio is approximately 42%. The company carries an S&P Earnings & Dividend Quality Ranking of A and the company is one of S&P's Dividend Aristocrats.

As is always the case, investors need to perform their own due diligence before investing in any of the companies mentioned on this site. As it relates to APD, the company has a hostile takeover bid on the table for Airgas (ARG).


Disclosure: long interest in APD


Bullish Sentiment Continues Decline And Market Moves Higher

The individual investor bullish sentiment reading for the week ending 3/17/2010 fell 9.9 percentage points to 35.37%. This level is below the average of the bullishness reading of 39.3%. Since January 13th, the less volatile 8-period moving average of the bullishness reading has declined from 42.9% to this week's reading of 36%. As investors have become less bullish, the market continues to trend higher.


Tuesday, March 16, 2010

Six Notable Dividend Increases So Far In March

Following are six companies in the S&P 500 Index that have increased their dividends so far in March.


Source: Standard & Poor's

Long Interest: GD, PEP, QCOM, WMT


Sunday, March 14, 2010

Fairholme Fund's Bruce Berkowitz Interview

On Consuelo Mack's WealthTrack series, she interviewed Morningstar’s Domestic Equity Fund Manager of the Decade Bruce Berkowitz, founder and lead portfolio manager of the five-star Fairholme Fund (FAIRX). Her interview took place late last year but his advice for investors is invaluable. Berkowitz will explain how he has beaten the S&P by more than 200 percent over the past decade and where he is finding value now.


Better Investing's Most Active Stocks

From time to time I review Better Investing's most active stocks as reported by its members. According to members' recent buy and sell decisions, as reported by a small, informal sampling -- 107 transactions -- for the trailing 4-week period ended March 14, 2010, following are the most active stocks.

Better Investing's most active period ending March 14, 2010Companies Profiles:
  • Petmed Express (PETS)
  • Ford (F)
  • Walgreen (WAG)
  • Stryker (SYK)
  • Life Partners Holdings (LPHI)
  • Jacobs Engineering (JEC)
  • Bank of America (BAC)
  • Oracle (ORCL)
  • General Electric (GE)
  • Berkshire Hathaway (BRK.A)

Long interest: WAG, SYK, BAC, GE and BRK.A & B.


Thursday, March 11, 2010

Bullish Investor Sentiment Rises, But...

Although bullish investor sentiment spiked higher this week, the 8-period moving average continued to decline. The American Association of Individual Investors reported that bullish investor sentiment increased to 45.29% versus the prior week's reading of 35.86%. The bullish sentiment level plus one standard deviation is about 50%. The 8-period moving average of the bullishness reading actually declined to 36.6% versus the prior week's average of 36.9%. This is the ninth straight week the bullish 8-period average has declined.


Monday, March 08, 2010

Market In Denial Phase Of Sentiment Cycle

A reader posted a comment/question on my article about February's performance of dividend payers versus non payers curious if the market sentiment is one where investors are in the denial phase of the sentiment cycle. Several articles today made reference to the fact investors are leery of the market at this stage, in part due to the strong advance off of the March 2009 lows.
Below is a 2-year chart of the S&P 500 Index (SPX) with notations that coincide with a chart that was first publish in 1991 by technical analyst Justin Mamis in a book titled The Nature of Risk. The chart depicts investor sentiment at various stages in the market's cycle.


The market will hit resistance at around the 1,150 level on the S&P 500 Index. Additionally, the recent advance has been occurring on lower volume that may be a sign of investors in disbelief regarding further advance at this point in the cycle.


In short, I believe investors appear anything but confident or enthusiastic at this juncture. Even fund flow data shows investors are placing more money into bond funds than into equity funds.


Monday, March 01, 2010

Dividend Payers' Return Lags Non Payers In February

The average performance of dividend paying stocks in the S&P 500 Index ($INX) underperformed the non payers in February, 4.15% versus 4.74%, respectively. On a year to date basis, however, the payers are outperforming the non payers, 1.57% versus -.24%.

dividend payers versus non payers performance February 2010With respect to dividend actions, February was a much improved environment compared to February of 2009. February tends to be the busiest month for dividend news and the S&P 500 index companies saw 45 increases versus just 30 in the same period last year. Additionally, there were no dividend decreases in February versus 18 decreases in February 2009. For the three month period ending in February, there were 79 positive announcements and just two reductions versus 58 positive announcements and 41 reductions for the same period in 2009.


Source: Standard & Poor's


The Market Is Like A Puzzle

As one puts together a puzzle certain pieces will fit and others won't depending how far along one is in completing the puzzle. Investments aren't much different. Certain types of investments will fit into ones portfolio based on where the economy is in the economic cycle.

I read an interesting post today by Tadas Viskanta, the author of the site Abnormal Returns. His post titled, Play the Ball where it Lies, offers an interesting perspective for investors as they evaluate buy and hold decisions. One premise in the article notes that the markets are rarely "normal" so an investor needs to know why they are making specific investment decisions. At the end of the day, an investor should know why they own what they own. The brief article is a worthwhile read.


Sunday, February 28, 2010

Dividends Will Be A Company's Renewed Focus?

Money manager Neil Hennessy of the Hennessy Funds believes companies will reward shareholders by initiating or increasing dividend payments. In the below video Hennessy explains why he believes company managements will have a heightened focus on dividends.


Saturday, February 27, 2010

Berkshire Hathaway's 2009 Annual Letter Is Out

The much anticipated 2009 Berkshire Hathaway (BRK.A) annual letter to shareholders, written by Warren Buffett, is now available on the company's website. This letter is always an interesting read by investors. I anticipate noting my thoughts on the letter later this weekend. The PDF version of the annual letter can be accessed on Bershire's Hathaway's website.


Thursday, February 25, 2010

The Impact Of Rising Interest Rates On Stocks And Bonds

One thing that seems almost certain is the next move in interest rates will be a move higher. What will a move higher in interest rates mean for stock and bond investors?

It should be noted longer term market rates have already been trending higher over the past twelve months. The 30-year U.S. Treasury rate has increased from around 3.5% a year ago to 4.6% today. Short term rates, i.e., the 1-month Treasury rate, has actually declined from around .20% a year ago to .08% today. In other words the yield curve has steepened. But back to the original question.

For a bond investor, higher interest rates will have a negative impact on the price of a bond or price of a bond mutual fund. The impact of this "interest rate risk" depends on the maturity or duration of a particular bond. In its simplest form, the duration indicates how much the price of a bond or price of a bond mutual fund will change given a 1% or 100 basis point change in interest rates. For example, if the duration of the bonds in a bond mutual fund is 5 years, then the price (NAV) of the bond fund will decline 5% (increase) for a 100 basis point increase (decrease) in interest rates. The question for investors then is how long does it take to recover the loss in principal.

In a recent research article from Charles Schwab (SCHW) titled, Should You Worry About Bond Funds if Interest Rates Rise?, it is noted that,
"More than 90% of the total return since 1976 generated from a broadly balanced portfolio of US investment-grade Treasury, agency and corporate bonds has come from interest payments as opposed to change in price..."
If an investor understands the recovery time, they will then know if their time horizon matches the term or duration of the bonds or bond fund.

For stocks they tend to perform better in declining interest rate environments as well. Unlike bonds though, on average, stocks have generated positive returns in rising interest rate environments as well as in declining rate environments. Although stock returns have tended to be positive in periods where interest rates have increased, the better returns are found in declining interest rate periods.

In Standard & Poor's article, Rising Rates Revisited, they include returns be S&P 500 sector as well.

For investors then, if one believes interest rates will trend higher over a period of time in which it will be necessary to access the principal invested, paying attention to the duration of an investment as well as the types of stocks within a portfolio will be important.

Source:

Should You Worry About Bond Funds if Interest Rates Rise?
Charles Schwab & Co.
By: Rob Williams
February 24, 2010
http://tinyurl.com/ylbmaeu

Rising Rates Revisited
Standard & Poor's
By: Sam Stovall
February 19, 2010
http://tinyurl.com/23j6med


Sunday, February 21, 2010

Investor Fund Flows Favoring Fixed Income Investments

The below chart notes the change in fund flows for the broad mutual fund asset classes of equity, fixed and money market funds. If the line is above the "zero" x-axis, then the respective asset class saw positive fund flows for the period in question. For the periods earlier than 2010, the data is monthly.

The chart shows fixed income funds have generated positive investment flows since September of last year. During that same time period, equity funds saw outflows except for a brief period in early January of this year. The negative flow in money market cash has been driven mostly by institutional investors. Retail investors have actually added to their money market funds since the beginning of February. Is this a contrarian sign?


Investors interested in reviewing the data for a longer time period, the Investment Company Institute website contains more detail on flow data.


Wednesday, February 17, 2010

2010 Dogs Of The Dow Performance Update

The year to date performance of the 2010 Dogs of the Dow are slightly ahead of the Dow Jones Industrial Average Index. As the below table indicates, the best performing Dow dog is Boeing (BA) with a YTD return of 14.2%. The worst performing dog is Verizon (VZ) returning a negative 12%. In 2009, the Dow Dogs slightly underperformed the Dow Index, 17.8 versus 18.8, respectively.


The "Dogs of the Dow" investment strategy is one where an investor ranks the thirty Dow Jones Industrial Average members by yield, highest to lowest, based on the last trading day of the prior year. An investor then invests an equal amount in the ten highest yielding Dow stocks and holds them for one year. More information on the Dogs of the Dow investment strategy and other variations on the strategy can be found at a website devoted to Dogs of the Dow investing.


Sunday, February 14, 2010

4 Dividend Increases Earlier This Month

February is the busiest month for dividend increases and below is detail on four companies increasing their payouts earlier this month.


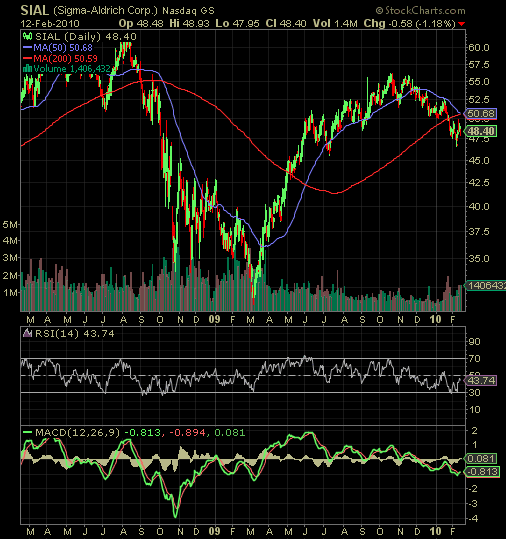
Sigma-Aldrich (SIAL)
  • announced a 10.3% increase in the quarterly dividend to 16 cents per share versus 14.5 cents per share in the same quarter last year.
  • based on 2010 estimated earnings per share of $3.14, the projected payout ratio is 20%. This compares to the 5-year average payout ratio of 20%.
  • SIAL carries an S&P Earnings & Dividend Quality Ranking of A+ and is one of S&P's Dividend Aristocrats.

United Technologies (UTX)
  • announced a 10.4% increase in the quarterly dividend to 42.5 cents per share versus 38.5 cents per share in the same quarter last year.
  • based on 2010 estimated earnings per share of $4.60, the projected payout ratio is 37%. This compares to the 5-year average payout ratio of 27%.
  • UTX carries an S&P Earnings & Dividend Quality Ranking of A+.

Archer-Daniels Midland (ADM)
  • announced a 7.1% increase in the quarterly dividend to 15 cents per share versus 14 cents per share in the same quarter last year.
  • based on June 2010 estimated earnings per share of $2.96, the projected payout ratio is 20%. This compares to the 5-year average payout ratio of 18%.
  • ADM carries an S&P Earnings & Dividend Quality Ranking of A and is one of S&P's Dividend Aristocrats.

Bemis (BMS)
  • announced a 2.2% increase in the quarterly dividend to 23 cents per share versus 22.5 cents per share in the same quarter last year.
  • based on 2010 estimated earnings per share of $1.92, the projected payout ratio is 48%. This compares to the 5-year average payout ratio of 49%.
  • BMS carries an S&P Earnings & Dividend Quality Ranking of B+ and is one of S&P's Dividend Aristocrats.


Disclosure: Long interest in UTX.


Saturday, February 13, 2010

The Value Is In Quality

For the period between the March low in 2009 and year end 2009, low quality stocks drove the market's move higher last year. The better return that was achieved in the lower quality equity assets in 2009 versus 2208 also occurred in other asset classes as detailed below.
Riskier Assets Outperform

With respect to stocks at this point in time, “If you go farther down on the quality scale, you are not getting a valuation discount,” said Cathy Seifert, head of financial services equity analysis at S&P. As noted in a number of my earlier blog posts, S&P's Quality Ranking measure looks at the growth and stability of a company's earnings and dividends over the prior 10-year period. S&P's research has noted that companies with above average quality rankings tend to outperform over the long run.

"S&P believes that high-quality stocks offer both increased safety of principal and potentially higher long-term returns versus low-quality issues,” says Richard Tortoriello, an S&P equity analyst. “We believe the recent market pull-back offers investors an opportunity to participate in a cyclical bull market. We would favor high-quality issues at this point."

A partial list of the stocks that carry S&P's 4 or 5 STAR rating and also have a buy rating by an S&P analyst is detailed below.


Disclosure:
Readers should assume I have a long interest in each company on the above list and/or may be selling an investment in one or more of the above companies at anytime.


Thursday, February 11, 2010

Conflicting Investor Sentiment Data

The sentiment data reported this week by the American Association of Individual Investors and Investors Intelligence is somewhat conflicting. The individual investor bullish sentiment as reported by AAII shows bullish sentiment rose to 36.75% versus last week's reading of 29.23%. Most of the increase in bullish sentiment came from those investors that were neutral last week. The neutral reading fell over six percentage points. On the other hand, the Investor Intelligence results show:
"bullish sentiment among newsletter writers is currently at 34.1%, which is the lowest level since March 2009. At the same time, bearish sentiment (26.1%) is the highest since November, while the percentage of newsletter writers in the correction camp has sky-rocketed all the way to 39.8%, which is a level that hasn't been seen since 1983," as reported by Bespoke Investment Group.


Tuesday, February 09, 2010

S&P 500 Index Finding Support

Just returned from several days of travel out of town visiting clients in Charleston, S.C. The city of Charleston is rich with history. I must say though, traveling by air is becoming less fun. Getting to a destination seems to take an entire day if you need to change planes along the way, which I had to do. Throw in some weather related delays and that just adds a little more to the travel adventure.

The market continues to look for direction in the face of the negative news related to sovereign debt issues in Greece. Today's market advance came on the back of a potential resolution of the debt crisis with the EU maybe stepping in to provide some support. The downside to this is the lack of moral hazard. As noted in a recent issue of The Economist magazine,
"A messy Greek default would harm almost everybody. As markets and governments know only too well, behind Greece stand others: Portugal, Ireland, Spain and even Italy, the world’s third-biggest sovereign debtor."
Back to the market. The S&P 500 Index (SPX) is attempting to find support around the 150 day moving average. The 200 day moving average is around 1,020. Since late January, the downside volume has been steadily decreasing with volume on up days staying level or trending slightly higher.


The market does appear oversold in the short run. The percentage of S&P 500 stocks trading above their 50-day moving average has declined to 22%. At the beginning of the year, this percentage reached nearly 95%.


Earnings reports for the 4th quarter have been coming in relatively strong. Rightfully so, the market has been focused on top line revenue results. Revenues have been coming in ahead of expectations, but still below year ago levels.


Sunday, February 07, 2010

Catching Up On A Few Dividend Increases From Last Week

Last week saw a number of companies announce increases in their dividends. Two notable increases were from L-3 Communications (LLL) and Colgate Palmolive (CL).

L-3 Communications and Colgate Palmolive dividend analysis table
L-3 Communications
  • announced a 14% increase in the quarterly dividend to 40 cents per share versus 35 cents per share in the same quarter last year.
  • based on 2010 estimated earnings per share of $8.15, the projected payout ratio is 20%. This compares to the 5-year average payout ratio of 16%.
  • LLL carries an S&P Earnings & Dividend Quality Ranking of A-.

Colgate-Palmolive
  • announced a 20% increase in the quarterly dividend to 53 cents per share versus 44 cents per share in the same quarter last year.
  • based on 2010 estimated earnings per share of $4.85, the projected payout ratio is 45%. This compares to the 5-year average payout ratio of 45%.
  • CL carries an S&P Earnings & Dividend Quality Ranking of A+.


Thursday, February 04, 2010

Decline In Bullish Investor Sentiment Continues

Today's release of the American Association of Individual Investor's sentiment survey shows individual investors continue to become less bullish on the market. The current bullishness level takes the bullish sentiment level near one standard deviation below the bullishness average. The bull/bear spread is reported at -14% versus last week's spread of -2%. As this is a contrarian indicator, this is one indicator that suggests the market could be in store for a bounce?


Tuesday, February 02, 2010

Dividend Payers Outperform Non Payers In January

For the month of January 2010, dividend payers in the S&P 500 Index ($SPX) outperformed non payers. January saw the Index decline 3.70% compared to the payers' decline of 2.48% and the non payers' decline of 4.75%. This past January was the first in the last three years where there were no dividend decreases or dividend suspensions for companies in the S&P 500 Index (updated 2/3/2010: Valero (VLO) reduced its dividend 66% in January). In declining markets, dividend paying stocks, and especially dividend growers, tend to hold up better than the overall market.