Tuesday, June 19, 2018

A Little Perspective And Balance Would Be Useful

Much of what has been discussed on financial news networks over the course of the past several days has centered on tariffs and the escalation into a potentially larger trade war. This is the type of negative news that the media enjoys pounding into its readers and listeners. Of course one should not put their head in the sand about potential consequences of an all out trade war, which we believe will not unfold though. To date the amount of product being impacted is just .25% of our economy. Adding some balance to the tariff discussion and the broader impact to the markets would be helpful. The one outcome I heard repeated today is the Dow Jones Index return is now slightly negative for the year. What about some of the broader indices though?

Below is a year to date chart showing the return of several indices and ETF's that represent the S&P 500 Index, the S&P Midcap Index (IJH), the S&P Small Cap Index (IWM) and the MSCI Emerging Markets Index (EEM). Clearly, all is not bleak. The small cap index is up 10.85% this year through the close on 6/19/2018. The nearly half year return for midcap stocks is a respectable 5.52% and the S&P 500 Index remains up 3.33%. Emerging markets have been the weak link and partially due to the tightening monetary policy in the U.S which I discuss a little later.


Tuesday, June 12, 2018

Small Business Optimism: 2nd Highest Level In 45-Year History

Today, the National Federation of Independent Business (NFIB) reported the May Small Business Optimism Index increased to the second highest level in the survey's 45-year history. The May reading increased 2.6 points versus the April reading and exceeded the high end of the consensus range.


Econoday reports:
"the rise in optimism among small business owners was broad-based, with 8 of the 10 components of the index showing improvement. Contributing to the overall gain were plans to increase inventories, which rose 3 points to a net 4 percent, earnings trends, rising 4 points to net 3 percent and a survey record, plans to make capital outlays, up 1 point to a net 30 percent, and expected credit conditions, which rose 1 point but remained negative at a net minus 5 percent."
Four out of last seven highest NFIB readings have occurred in the last eighteen months. As the below chart shows, historically, 1-year subsequent returns for the S&P 500 Index have generally been strong following high levels of small business optimism. Going forward I will include tracking of the equity market's performance based on this new high reading as well.


Sunday, June 10, 2018

Another Look At Growth Versus Value

Writing blog commentary serves as a permanent record of one's thoughts at a specific point in time. When reflecting back on earlier posts, expectations and conclusions do not always unfold in the market or economy as anticipated and written about at that time. The benefit is one can adjust future thinking and conclusions if necessary. Sometimes events occur that one simply could not anticipate and the events result in a change of direction in the market. All investors would benefit in tracking how they arrived at their investment decisions..

It seems over the last few weeks there has been much written about the outperformance of growth stocks versus value stocks. The extended outperformance of growth over value has pushed the relative valuation to a high for the growth style and a low for the value style and was referenced with a chart in the June monthly presentation by State Street Global Advisors. The below chart is a slightly different version but shows the higher relative valuation of large cap growth versus large cap value at this point in time.


Wednesday, June 06, 2018

One Chart Will Not Predict The Next Recession

I had the fortune to read an article yesterday, Uh-oh: Unemployment Falls Below 4%, that noted,
"On each occasion that the unemployment rate sank beneath 4%… recession was soon on tap. To remind, it now rests at 3.8%. But why should recession rapidly follow peak employment?"
The article included the below chart and provided several reasons that would seem to justify the fact a recession is near when the unemployment rate is below 4%. Often times these scary or miracle charts are highlighted in an attempt to scare investors out of the market.


Sunday, June 03, 2018

Record Levels Of Strength In Economic Sentiment Reports

As regular readers of this blog know, from time to time I opine on investor sentiment whether it is the AAII Sentiment Survey, the Investor Intelligence Advisors' Sentiment report or the NAAIM Exposure Index. At the moment, suffice to say that these 'investor' sentiment reports are neither overly bullish or overly bearish and conclusions drawn from them are most useful when the data are at extremes. Below is a chart of last week's bullish reading from the AAII Sentiment Survey and its current reading falls between + and - the one standard deviation levels.


Sunday, May 27, 2018

Only The Good News

As seems often the case, it is the bad news that leads headlines and garners the attention of those interested in digesting news reports. In the current economic environment though it seems somewhat difficult to promote the bad news when there seems little of it. I am not saying there is no bad news, but much of the news today that is related to the market and the economy is decidedly positive, however, from my perspective this good news does not seem to get much press. So, below are highlights of some of the positive news that may be of interest to investors.

The Consumer:

The consumer segment accounts for 70% of economic growth and post the financial crisis in 2009, the consumer seems in very good shape.
  • debt payments as a percentage of disposable personal income is lower than the pre-financial crisis level and below the level at the beginning of 1980.


Saturday, May 26, 2018

Potential For A Stronger Second Half In Stocks

Seems as though much has taken place in the first five months of this year that is newsworthy and impactful to the markets, i.e. Iran, North Korea, tariffs, an increasing 10-year yield, and I could go on. With the volume of news flow though, the equity market has essentially traded sideways this year with the S&P 500 Index price return equaling just 1.78%.


Sunday, May 20, 2018

Dollar Strength Leads To Large Cap Stock Outperformance

A recent strengthening of the US Dollar has some investment commentary now favoring small cap stocks over large cap stocks. This is partly due to the earnings headwind that can negatively impact multinational companies as they convert foreign earnings back into the Dollar. One recent report titled, Rising Treasury Yields And Dollar Completely Change Investment Themes, noted:
"The resumption of the bull market has taken shape in the form of small caps. I fully expect that the rest of the market will follow suit eventually, but rising treasury yields and the surging dollar have money rotating feverishly into smaller companies and that relative strength is likely to continue."
In the below chart, a downward trending red line indicates small cap stocks are outperforming large cap ones. In 2018 small cap stocks have outperformed large cap stocks while the US Dollar Index (DXY) has risen from below 90 to almost 94.


Thursday, May 03, 2018

Investor Sentiment Continues To Be Less Bullish

This week's Sentiment Survey report from the American Association of Individual Investors continues to show a falling trend in the level of bullishness of individual investors. This week's bullishness reading was reported at 28.4% and down from 36.9% in the prior week. The current bullishness reading is near the minus 1 standard deviation level and these sentiment measures are most useful as a contrarian indicator at extremes. In January of this year the bullishness reading reached near 70% and subsequent market returns have trended lower since then. AAII published an article, Is the AAII Sentiment Survey a Contrarian Indicator?, that provides insight into the market's return at various sentiment levels.


Heightened Volatility A Result Of The Change In The Earnings Growth Rate

Investors are experiencing a market exhibiting a higher level of volatility. This heightened volatility is more normal than the lack of volatility experienced in the few years leading up to 2018 and yet the S&P 500 Index is down less than 2% this year.


Wednesday, April 25, 2018

Consumer In Decent Shape, A Positive For Continued Economic Growth

In spite of the market's negative reaction to some of the recent earnings reports issued by credit card companies, one might think the individual consumer is in pretty bad shape. To the contrary though. About a year ago I evaluated the consumer as a result of issues surrounding some of the credit card firms. As was the case in the earlier blog post, the consumer data today is indicative of a consumer that is not overly burdened with debt repayment.

The following three charts provide a visual picture of the debt service burden on consumers along with various charge-off and loan delinquency rates. The first chart represents the Household Debt Service Ratio which is debt payments as a percentage of disposable income. The current ratio of 10.3% is just slightly above the year ago level of 10% and remains below levels seen at the beginning of prior recessions.


Sunday, April 15, 2018

Dividend And Stock Buyback Growth Potentially Accelerate In 2018

Near the end of last month S&P Dow Jones Indices reported preliminary dividend and buyback activity for the S&P 500 Index for the fourth quarter of last year. For the quarter the dollar amount of dividends paid increased 5.4% versus the same quarter in the prior year. Additionally, for the quarter, dividends combined with buybacks increased 3.1% year over year. It is not uncommon for the combined dividends with buybacks to exceed as reported earnings in the quarter and that was the case for Q4 2017 as seen in the below chart.


Thursday, April 12, 2018

Sentiment Now Broadly Bearish

In prior posts highlighting investor sentiment data it has been noted that sentiment data is more actionable at market bottoms than at market tops. Knowing this, the American Association of Individual Investors reported bullish investors sentiment at 26.1%, which is below the minus 1 standard deviation level of the average bullish sentiment level.


Additionally, bearish sentiment jumped 6.1 percentage points to 42.8% resulting in the bull/bear spread being reported at a negative 16.7 percentage points, the widest negative spread in more than a year.


Also, newsletter writers are far less bullish with the bullish sentiment falling to 42.2% from nearly 70% at the beginning of this year. The Investor Intelligence Advisors' Sentiment bull/bear ratio has fallen to nearly 2:1 versus over 5:1 at the beginning of the year as well. The II Advisors' Sentiment Survey studies over a hundred independent market newsletters and assesses each author’s current stance on the market: bullish, bearish or correction.


With much of the sentiment now decidedly bearish, just possibly the market is nearing a bottom.


Wednesday, April 11, 2018

US Dollar Influencing Oil Prices

Nearly two years ago four factors were influencing the energy market and specifically the price of oil. 
  • Oil inventory in the U.S. hit a record high
  • The price of crude (West Texas Intermediate or WTI) reached a post financial crisis low
  • Rotary oil rig count hit a record low of 404
  • The trade weighted value US Dollar hit a post financial crisis high
The fact oil inventory spiked is partially attributable to technological advancement in drilling and specifically, increased supply from fracking activity. The subsequent low level of drilling activity that began a few years ago contributed to the supply decline. Today, the rig count has once again moved higher and the oil market may be seeing a potential bottoming of the supply decline, yet oil prices continue to move higher as seen in second chart below.


Tuesday, April 10, 2018

Spring 2018 Investor Letter: Noise Versus Fundamentals

In one brief quarter, the equity market goes from experiencing virtually no volatility to seemingly +/- 2% swings on a daily basis. Last year was a bit abnormal and more a year of consistent returns and minimal drawdowns. In fact, the largest drawdown was just 3%. The market has already experienced a 10% drawdown in 2018. In our Spring 2018 Investor Letter we note the fact the first quarter broke a string of nine consecutive positive quarters for the S&P 500 Index. Investors have been fortunate by the length of this positive cycle, however, recent experience can often lead one to expect “more of the same.” This expectation or behavior is referred to 'recency bias' and we discuss its implication for investors in our Spring Investor Letter along with our firm's thoughts for the coming year.

For additional insight into our views for the market and economy in the coming year, see our Investor Letter accessible at the below link.


Monday, April 09, 2018

Tariffs, Stocks And Recessions

One truism investors know well is the fact the stock market does not perform well in a recession. The recent focus on implementation of tariffs on the U.S.'s largest trading country, China, have some concerned about escalation into an all out trade war and leading to an economic slowdown or recession. Google web search on the term 'Tariffs' has moved higher with the March 1 peak coinciding with the  rebound peak for the S&P 500 Index around the same time.


Thursday, April 05, 2018

Not A Unique Equity Market: Higher Prices Ahead?

About a year and a half ago I wrote a post on the current equity market that broke out of a thirteen year trading range in 2013 and compared it to the bull markets of the 1950s and 1980s. A number of policy issues being pursued today have similarities to ones in those two decades and below is a brief summary of what I wrote then:
"...potential commonality to the current market compared to those prior decades related to policy decisions coming out of Washington, D.C. In the 1950's the Gross National Product in the U.S. more than double from 1945 to 1960. Government spending in the 1950's was targeted at construction of the interstate highway system, building of schools and an increase in military spending. In the 1980's President Reagan's policies focused on reducing the tax burden on Americans, lowering government regulation and shrinking government itself. President Elect Donald Trump also projects to implement similar policies, i.e., reduce regulation, shrink the government, increase spending on infrastructure and lower taxes. For investors the question to answer is what market segments worked then and might these same sectors outperform early in a Trump administration."
An update to a chart in that earlier post is shown below and in spite of the size of the 'point' swings in the market today, the path of this current bull market is not unique. If history is any guide, and given similar policies out of Washington as in the 1950's and 1980's, the S&P 500 Index certainly appears to have more room to the upside. In fact, the market maybe nearing a point of a sustained upside move.


One thing investors experienced in the first quarter was a return of volatility to the equity markets, and the bond market for that matter. Wednesday's market action was a perfect case in point as the Dow Jones Industrial Average traded down over 500 points near the open yet closed up 230 points, a trading range of more than 700 points. The catalyst for the market swing seems to be connected to the discussion around tariffs and the potential negative implications resulting from the tariff negotiations. I stress 'negative' as most of the tariffs have not been instituted, yet it is the unknown that can cause difficulty for the equity markets.

I can list a number of additional potential negative issues with any single one being a headwind for the equity market: rising interest rates and consequent flattening yield curve, growth in deficit spending out of Washington and more. All but the interest rate factor are mainly political events and I would say business fundamentals and economic fundamentals remain more important variables for the market right now. Given some of the negative factors cited, just maybe the market will climb the proverbial wall of worry.

I am not recommending burying one's head in the sand regarding some of these potential headwinds. What is important though is not to place out sized weight on the 'noise' at the expense of underlying fundamentals. Importantly, policies being pursued today have similarities to policies implemented in earlier decades and those policies were bullish for stocks then.


Monday, April 02, 2018

A More Challenging But Normal Equity Market

Before I left for a week of vacation at the end of March, the equity markets had begun to exhibit a higher level of volatility. This seems to occur more often than not around this time period each year. This heightened volatility was to the downside and I wrote a post before leaving town noting this was more typical market action. What has been so abnormal about the equity market over the past five years is the fact nearly every calendar quarter since 2013 has generated a positive return. As the below chart shows, prior to 2013, this was certainly not the case.


Saturday, March 24, 2018

Recent Equity Market Weakness A Symptom Of A More Normal Market

This past week was certainly a difficult one for the market and by default, a difficult one for investors. Most of the weakness occurred on the last two days of the week, which resulted in the week's return for the S&P 500 Index ending at a negative 5.98%.


Thursday, March 15, 2018

Improved Earnings Growth Expectations Broadly Reduce PEG Ratios

Before passage of The Tax Cuts and Jobs Act in December, earnings growth for the S&P 500 was expected to be low double digits in calendar year 2018. Since passage of tax reform, a significant improvement in earnings growth expectations has occurred. The below table shows I/B/E/S earnings growth expectations in October by sector and for the S&P 500 Index compared to expectations as of the end of last week.


Tuesday, March 13, 2018

Near Record Small Business Optimism

Today the National Federation of Independent Business (NFIB) reported small businesses are showing unprecedented optimism. The NFIB Small Business Optimism Index was reported at 107.6, the second highest reading in the 45-year history of the Index. The highest reading recorded was 108.0 in 1983.


Monday, March 12, 2018

Bond Yield To Stock Yield Spread Sufficiently Wide To Challenge Stock Returns

A little over a year ago I noted the yield on the 10-year Treasury surpassed the dividend yield of the S&P 500 Index. With rising bond yields, there becomes a point when the bond yield is sufficiently high relative to the yield on stocks that bonds can challenge stock returns. In that earlier article I referenced a research article written by CFRA Research's Sam Stovall and titled, Rising Prices, Shrinking Yields. In the research article it was noted prospective stock returns became most challenged when the yield on the 10-year U.S. Treasury exceeded the dividend yield of the S&P 500 Index by at least one full percentage point, i.e. 100 basis points. The forward return at varying spreads is detailed below.


Sunday, March 11, 2018

Individual Investors Favoring Technology Stocks

Periodically I review the most active stocks individual members of Better Investing indicate they are purchasing. A notable feature on the current list is the fact technology related stocks are dominating member purchases.


Additionally, after the market's close on Friday, I posted a tweet noting Fidelity customers' top purchases. Again, technology stocks are gaining the interest of Fidelity's individual investors.


With both the technology sector SPDR (XLK) and the Nasdaq Index both achieving record highs on Friday, one might believe the technology sector is getting over heated. The interest in technology has led to acronyms for various groups of stocks, with the most familiar being the FAANGs, representing Facebook (FB), Amazon (AMZN), Apple (AAPL), Netflix (NFLX) and Google (GOOGL), now known as Alphabet. As the below chart shows, the technology sector in the S&P 500 Index accounts for 25.2% of the index weighting and is approaching the technology bubble peak of 32.9%. One major difference today though is the fact the valuation of the technology sector holdings is not even close to the bubble peak valuation. At the height of the technology bubble in 2000, the technology sector P/E equaled 82 times trailing earnings. Today, the trailing technology sector P/E is 23 times earnings.


In spite of the fact a few technology or technology related stocks trade at higher P/E multiples, the valuations are far from bubble levels seen in 2000.


Friday, March 09, 2018

Sentiment And Economic Data Laying The Foundation For Higher Stock Prices

The headline number of an increase of 313,000 in February's non-farm payrolls this morning was big. This is the largest monthly increase since July 2016. The high end of consensus estimates was for a 230,000 increase in payrolls. December and January reports were also revised higher.


Thursday, March 08, 2018

Trade Deficit And Tariffs: It Is Complicated

President Donald Trump's announcement that he is instituting tariffs on imported steel and aluminum came as a surprise to some although reducing the trade deficit was one of his campaign promises. Dealing with the trade deficit issue is a complicated one since no one factor impacts trade. What is complicating a necessary discussion at the moment is the vitriol in which President Trump's tariff proposal is being discussed. For example, the media repeated commentary that the market would collapse once President Trump signed the tariff executive order; yet the S&P 500 Index closed almost .50% higher today.


Sunday, March 04, 2018

Rising Interest Rates A Headwind For Dividend Paying Stocks

Since July 2016 the yield on the 10-year US Treasury Note has increased from 1.32% to nearly 3% today. This doubling of longer term interest rates is creating a headwind for dividend paying stocks resulting in their underperformance versus their non-dividend paying counterparts as well as the broader S&P 500 Index.

The maroon line in the below chart represents the total return for the S&P 500 Index divided by the total return for the iShares Select Dividend ETF (DVY), When the maroon line is moving higher, the S&P 500 Index is outperforming the iShares Dividend ETF. Clearly the broader S&P 500 Index has been outperforming the dividend payers since July 2016. The blue line on the chart represents the yield on the 10-year U.S. Treasury Note and it is not a coincidence that the dividend payers are underperforming just as the 10-year Treasury yield began to rise in July of 2016.


Saturday, March 03, 2018

Sentiment And Economic Data Mostly Positive

A colleague and I just returned from a week long trip in south Florida visiting some of our clients on both the east and west coast of the state. One notable factor was the very high level of activity everywhere we visited. Restaurants were all packed, road traffic was unbelievably jam packed and the number of semis on the road seemed higher than usual, and usually those trucks do not drive around empty. We visited a new golf course development and the activity was anything but recessionary like. The bottom line is sentiment is highly positive and supports recent economic data releases focused on sentiment and economic indicators.


Saturday, February 17, 2018

Continuing To Favor U.S. Large Cap Stocks Over U.S. Small Cap Stocks

With the passage of tax reform, one market segment one might believe experiences an outsized benefit to earnings is U.S small cap stocks. This certainly seems plausible due to the fact smaller companies tend to have less direct exposure to foreign revenue; therefore, likely generating most of their profits in the U.S.

Our firm exited completely the U.S. small cap space in late 2013 based on a number of factors, with one being the relative valuation of small cap stocks versus large cap stocks. Reviewing the relative valuation of small caps versus large caps based on price earnings ratios has certainly turned to favor small over large as can be seen in the chart below.


Wednesday, February 14, 2018

Small Businesses Remain Highly Optimistic

Tuesday's report by NFIB on small business optimism for the month of January places the reading in the top five highest coming in at 106.9. According to NFIB the response to "Now Is A Good Time To Expand" was 32% and is the highest level for this category in the Indexes 45-year history. Today's strong NFIB report comes on the heals of a record level of optimism in 2017. NFIB President and CEO, Juanita Duggan noted,


Tuesday, February 13, 2018

Enhancing Investment Results By Utilizing An Investment Mentor

In a recent article, Strong Hands - Bridging the Behavior Gap, by Pim van Vliet, PhD, a Managing Director at Robeco Institutional Asset Management, it was noted that,
"the average mutual fund investor lags a buy-and-hold strategy by -1.9%. This finding is persistent across different styles, varying from -1.3% for value investors to -3.2% for growth investors. Also 'passive' investors in market funds underperform a buy-and-hold strategy by a whopping -2.7%."


Monday, February 12, 2018

Dow Dogs Struggle Early In 2018

The Dogs of the Dow of 2018 include two newcomers, General Electric (GE) and Procter & Gamble (PG). These two stocks made the list of top 10 dividend yielding stocks in the Dow Jones Industrial Average Index for 2018 and replaced Boeing (BA) and Caterpillar (CAT). Unfortunately the new additions are weighing down the performance of the Dow Dogs so far this year as they are the worst performing stocks out of the ten Dow Dogs year to date through Friday's market close.


Sunday, February 11, 2018

Last Week Was The Beginning Of An Equity Market Returning To Normality

Some are saying last week's market movement is one for the record books. I have seen descriptions noting the market decline was unprecedented or the market is in turmoil. S&P Dow Jones Indices Indexology Blog titled a post, I'm Exhausted, but outlines data that places the market decline in perspective. One data point in S&P's post,
"Keeping perspective, as repeatedly noted, while 1000 point declines make for frightening headlines, the percentage changes represented by those moves are not uncommon. To wit, there have been nearly 300 daily 4% or greater moves since the DJIA’s inception. Put another way, 3 of the top 10 worst point drops on record occurred during this recent spell; none of them, however, come anywhere near the worst percentage."


Thursday, February 08, 2018

A Reversal In Bullish Investment Sentiment

I have often written that sentiment measures are most valuable at their extremes. Also, they tend to be most representative of potential market turning points when the extreme is at the bearish end of the spectrum. However, in hindsight, it appears recent excessive bullishness for individual investors and institutional investors indicated a cautionary equity market outlook would have been profitable.

The first chart below represents individual investors' bullish sentiment responses as reported weekly by The American Association of Individual Investors. On January 4 of this year bullish sentiment spiked to near 60% and represents a high level for this reading. About a month later, the 8-period moving average reached near 51%, also a high level for the 8-period average, although the average has exceed 60% in the past. 


Tuesday, February 06, 2018

Volatility Returns

Unwelcome, Unpleasant, Inevitable. The recent spike in volatility has certainly caught the attention of investors over the past several days and as corrections go, the market drop has been quick and sharp. 


Tuesday, January 30, 2018

Pullbacks Are A Normal Part Of A Bull Market

During the Fed's move to increase short term interest rates, some have expressed concerns due to the yield curve's increased flattening, i.e., short rates moving higher versus long term interest rates. This increased flattening move can be seen in the below chart and the concern centers around the fact that every recession since 1960 has been preceded by an inverted yield curve, i.e., short term rates higher than long term rates. The move by the Fed to push short term rates higher is part of a normal process to get interest rates back to a normalized level.


Saturday, January 20, 2018

Will The Stock Market Ever Decline Again?

For many investors it may seem difficult to believe since it has been so long ago, but the equity markets do go through negative returning periods. The average intra-year decline for the S&P 500 Index since 1980 is 14% and the last double digit decline was in February 2016, nearly two years ago. So what in the world is going on that has stocks in what seems an uninterrupted climb?

The below 'monthly' chart shows the S&P 500 Total Return Index since the beginning of 2016. Over the course of the two years, 2016 and 2017, the S&P 500 Index has experienced only three negative returning months (red bars) with no down months in 2017. The last bar on the chart represents the January 2018 return and the start of this year has been decidedly bullish.


Saturday, January 13, 2018

A Balancing Oil Market, But Will It Last?

In May 2011 crude oil (WTI) hit $113 per barrel and remained elevated at or near that level until the summer of 2014. Given the high price of crude and the expansion of fracking at that time, crude supply continued to grow until peaking in mid 2017. I wrote about the high crude supply level in mid 2017 and its impact on keeping oil prices down, Higher Oil Prices Contend With Too Much Supply And Higher Energy Efficiency. Today, we are seeing crude oil inventory decline at a fairly rapid rate as can be seen with the green line in the below chart.


Thursday, January 11, 2018

Investor Sentiment More Actionable At Market Bottoms

Today's weekly AAII Sentiment Survey reports a drop in bullish investor sentiment of 11.1 percentage points to 48.7%. The bullish sentiment reading has been on a steady move higher since November 16 when the bullishness reading was 29.4%. The weekly readings tend to be more volatile and one can look at the 8-week moving average in order to eliminate some of this volatility. As a result, although the sentiment reading fell this week, the longer period average of bullish sentiment increased to 45.6%, largely due to dropping the 29.4% bullishness reading from November 16.


Wednesday, January 10, 2018

Winter 2017 Investor Letter: An Uninterrupted Climb

Our Winter 2017 Investor Letter provides commentary on 2017 and our thoughts and observations on the coming year. Many strategists and investors have either commented on or know from first hand experience, in 2017 the equity market saw very little downside market volatility. Our expectation for 2018 is the market will see a more normal level of volatility. As we comment on in our Investor Letter, that normal level of volatility would be a 14.1% decline from peak to trough. A decline of that percentage amount would equal 3,500 Dow points, and that would represent a normal pullback.


For additional insight into our views for the market and economy in the coming year, see our Investor Letter accessible at the below link.


Monday, January 08, 2018

High Beta Stock Outperformance Suggests A Strengthening Economy

For the first part of 2017 low volatility equities were outperforming their high beta counterparts. However, as tax reform talk began to look more a reality in late August, high beta stocks resumed their outperformance that really began in early 2016. As the maroon line in the below chart shows, this high beta outperformance is carrying over into the beginning of 2018.


Sunday, January 07, 2018

Sentiment: Simply More Buyers Than Sellers

I am re-reading Justin Mamis' book, The Nature of Risk, a worthwhile read by the way, and being reminded of the dissemination of information prior to the internet age, which is difficult for many to believe if they did not work in investments at that time. Simply gauging market sentiment prior to each day's market open at that time was much different than it is today, of course. As he notes in his book, when one inquired about, say, a higher market, the most appropriate answer was there simply were "more buyers than sellers" that day. In today's proliferation of business cable channels, that type of response will not sell many advertisements.

This focus on buyers and sellers is really an evaluation of investor sentiment and is one reason I write about sentiment reports on a fairly regular basis. To that end, the American Association of Individual Investors reported Sentiment Survey results last week and individual investor bullish sentiment jumped 7.1 percentage points to 59.8%. Most of this bullish improvement came from the prior week's bearish survey participants as bearish sentiment decline 5.1 percentage points to 15.6%. This spike in bullish sentiment can be seen in the below chart.


Saturday, January 06, 2018

Dow 30,000 By Year End

The Dow Jones Industrial Average pushed through 25,000 in the first week of 2018. True to form, the President weighed in on this record and indicated 30,000 is the next target, skipping over the 1,000 increment target milestones. His comment was replayed numerous times on television by the financial media Thursday with many commentators spinning his comment as hyperbole, but might a Dow target of 30,000 in 2018 be reasonable?

The below chart displays the calendar year returns for the Dow Jones Industrial Average going back to 1980. Also included on the chart are red dots representing the largest intra-year drawdown or decline. Looking at the mid 1990's returns, there was a five year period, 1995 - 1999, where the Dow returns ranged from 16% to 33%, but with four of the year's return above 20%. So what would it take for the Dow Index to hit 30,000? A 20% return.


The point being, with the Dow Index trading at a large absolute number level, these 1,000 or 5,000 point moves are not out of the realm of even a reasonable possibility. Just as today a 100 or 200 point decline in the Dow is not a significant drop at all, i.e., less than a tenth half of a percent. Importantly for the market and investors though, is the fact the market has not experienced a double digit pullback since February of 2016, nearly a two year period. The market will experience one of these double digit declines as it did 1997 and 1998, but looking at those prior years, the market can recover and generate strong returns for the entire calendar year period.


Tuesday, January 02, 2018

Equal Weighted Equity Performance Lagged In 2017

One equity market phenomenon that played out in 2017 was the fact larger capitalization stocks were larger contributors to market returns. One way to evaluate this is to review the return of the cap weighted S&P 500 Index versus the equal weighted Guggenheim S&P 500 Index (RSP). As the below chart shows, the equal weighted index underperformed the cap weighted S&P 500 Index by more than 300 basis points. Additionally, the largest 50 stocks by capitalization (XLG) outperformed both the the S&P 500 Index and the equal weighted S&P 500 Index.


Monday, January 01, 2018

Is The Glass Half Full Or Half Empty

The end of Friday trading was certainly interesting as the last thirty minutes of the trading day incurred most of the day's half of a percent loss. A few Twitter posts I read were comments in the vain of "this is the selling I have been anticipating." The market is over due for a pullback.


Sunday, December 31, 2017

Most Read Articles From Our Blog In 2017

Below is a list of the most read blog articles in each month during 2017. One interesting commonality for some of the top posts is the fact the ones focusing on investor sentiment tend to gain higher levels of readership. Sentiment is one important market factor we monitor on a fairly regular basis. Secondly, some prior articles seem to remain applicable as 2018 is set to begin. For example, articles like Market Pullbacks Should Be Expected and The S&P 500 Index Is Expensive and Has Been So Since The Early 1990's are certainly timely even today.

Our firm's bullish equity stance in 2016 and 2017 has certainly rewarded our clients. We are in the midst of finalizing our Winter Investor Letter which will contain some of our firm's thoughts on the coming year.

To our clients and readers, we wish all of you a Healthy and Prosperous New Year.

Second Longest S&P 500 Rally Since 1932 - January 25, 2017

Recent Outperformance Of Low Volatility A Sign Of Risk Off Ahead?
- February 12, 2017

Time To Reduce One's Equity Exposure? - March 1, 2017

Widespread Bearishness Indicating Market Nearing A Turning Point? - April 14, 2017

The Unfortunate Rise Of The Misleading 'Scary Chart' Comparisons Again
- May 29, 2017

Market Pullbacks Should Be Expected
- June 26, 2017

Strong Earnings Growth And Favorable Valuations Lead To Weak Stock Returns - July 22, 2017

The S&P 500 Index Is Expensive And Has Mostly Been So Since The Early 1990's
- August 5, 2017

Stocks Need Some Healthy Competition - September 16, 2017

Citgroup Economic Surprise Indices Have Little Bearing On Equity Market Performance
- October 15, 2017

Individual And Investment Manager Sentiment Is Diverging - November 2, 2017

If Cash Is King - December 19, 2017


Thursday, December 28, 2017

Continued Improvement In Bullish Investor Sentiment

In the few weeks after the 2016 presidential election, individual investor bullish sentiment spiked to near 50%. Over the course of the next five months though, bullish sentiment trended lower to a year low of 23.85%. From March through April the market had some volatile periods that may have influenced investor sentiment; however, true to form this year, the market never experienced a prolonged or significant contraction.


Sunday, December 24, 2017

Dogs Of The Dow Make Up Ground In Second Half Of This Year

Four trading days left until the calendar turns to 2018 and one will be able to determine the list of stocks that will comprise the Dow Dogs of 2018. The Dow Dogs were laggards in the first half of the year, but have made up significant ground in the second half of 2017. To date the Dow Dogs of 2017 have outperformed the S&P 500 Index on a total return basis due to the Dogs higher dividend yield. However, the Dogs of the Dow have underperformed the Dow Jones Industrial Average Index on both a price only and total return basis. The best performing Dow stock that is not included in the Dow Dogs this year is Apple (AAPL) and the stock is up 51.1%.

The Dogs of the Dow strategy is one where investors select the ten stocks that have the highest dividend yield from the stocks in the Dow Jones Industrial Index (DJIA) after the close of business on the last trading day of the year. Once the ten stocks are determined, an investor invests an equal dollar amount in each of the ten stocks and holds them for the entire next year. The popularity of the strategy is its singular focus on dividend yield.


As of Friday's close both Boeing (BA) and Caterpiullar (CAT) will drop out of the Dogs for 2018. The two holdings in the running for inclusion in next year's portfolio are Procter & Gamble (PG) and General Electric (GE) with dividend yields of 2.99% and 2.74%. respectively.


Thursday, December 21, 2017

Small Business Optimism And Equity Market Return One Year Later

When the NFIB Small Business Optimism reading for December 2016 was announced in January, the December reading jumped 7.4 points to 105.8. At that time the optimism reading was the fifth highest reading recorded by NFIB. Prior instances of strong optimism readings were followed by positive stock market returns in the subsequent twelve months. NFIB's Small Business Optimism report last week closed out the subsequent twelve month period from the December 2016 reading and the stock market did not disappoint. As the below chart shows, the S&P 500 Index was up over 18% from December 15, 2016. The market's return was the best performing one out of the other four top NFIB readings. 


As noted in an earlier post, last week's NFIB Small Business Optimism report has the index at its second highest level in its 44-year history.


I will begin tracking the market's performance over the next twelve months and will evaluate the return. If history rhymes at all, 2018 stock market returns would be positive.


Is Optimism Too High?

One of my more regular topics that I write about on the blog from time to time is an update on sentiment measures, both individual and business. Sentiment might be viewed as the third leg of a stool, with the other two being the economy and business financial health or earnings growth. Without positive sentiment from businesses and investors, the economy is more likely to see lackluster growth. What got me to thinking about whether optimism is too high or not was a recent post by Josh Brown whose blog is titled The Reformed Broker.


Tuesday, December 19, 2017

If Cash Is King

Much has been written about the stock market's advance since the end of the financial crisis in 2009. Without getting into the valuation issues, as I have written about that for maybe too many times, the recent return, nearly past two years, has been pretty remarkable and has occurred with a very low level of volatility.


Business and consumer optimism is high, institutional investor optimism is high and individual investor optimism is rising. Almost seems as good as it can get from a sentiment perspective. We know corporations are sitting on a lot of cash with large amounts trapped overseas. The tax bill working its way through Congress is addressing this issue via a change on the taxation of cash held outside the U.S. This increase in corporate cash seems to be an issue that has developed over many years as can be seen in the two charts below. The first chart notes the absolute dollar amount of the cash while the second chart shows corporate cash as a percentage of GDP.


With the passage of a tax reform package, undoubtedly, corporate cash will likely be used in a number of different ways. Recently, Factset reviewed how companies responded to the tax holiday in 2004. Factset's analysis notes:
"In 2003, a combined $30.3 billion in special dividends was paid to shareholders of S&P 500 constituents  this figure jumped to $179.4 billion in 2004, an increase of 492%. In 2005, aggregate special dividends fell to $49.2 billion. Of this $179.4 billion, a collective $149.8 billion (84%) came solely from companies in the GICS Information Technology sector. Notable companies such as Microsoft (MSFT-US) and Motorola (MSI-US) contributed the most to this total. Financials and Healthcare were also top contributors."
And finally, at the end of the day, there will likely be demand for stocks outside of just corporate buybacks. As the below chart shows, both in absolute terms and as a percentage of GDP, household deposits are far above pre-financial crisis levels. As a percentage, deposits are nearly 60% of GDP. If cash is king, individual investors are sitting on potential fuel for the next move higher in equities.


Disclosure: Long MSFT


Companies Begin Highlighting Earnings Benefit From Tax Reform

It seems a day does not go by where the market's valuation is a front and center topic of discussion. Suffice it to say that I believe, and have written as such recently, that the market does not correct simply because it may be trading at an elevated valuation. Although market declines or pullbacks have been few and far between, when the next pullback occurs, a factor in the the magnitude of the decline will likely center on the market's valuation.

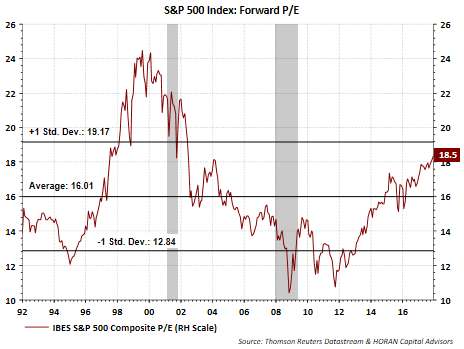
The below chart shows the current market P/E where the earnings are based on the 12-month forward earnings estimate supplied by I/B/E/S. Certainly the P/E is elevated at near a +1 standard deviation level, still the current P/E is quite a bit lower than the technology bubble valuation peak of near 25 times earnings.


Overall earnings growth will be important for the equity market to generate respectable returns in 2018. With passage of a tax reform package nearing realization, companies will benefit from the decline in the maximum corporate tax rate. As an example, tonight FedEx (FDX) reported earnings and noted in the conference call that a lower tax rate will add $.85 to $1.00 to per share earnings. This represents an earnings boost of 8% based on currently expected May 2018 earnings of $12.45 per share. What the tax bill does for many companies is provide an earnings benefit that will result in a reset of the market's valuation to a lower level. The result is the market's valuation is closer to its long run average of 16 to 17 times earnings.

Disclosure: Long FDX


Thursday, December 14, 2017

A Spike Higher In Bullish Investor Sentiment

Today the American Association of Individual Investors reported results of their Sentiment Survey for the week ending 12/13/2017. The report shows individual investor bullish sentiment jumped 8.1 percentage points to 45.0%. 


Most of the jump in bullish sentiment was a result of a 6.1 percentage point decline in bearish sentiment. This has resulted in the bull/bear spread widening to 16.9%, the third widest spread in 2017.


As I have noted in prior sentiment updates, the survey results can be volatile and the 8 period moving average removes the weekly volatility. Additionally, the sentiment measures are contrarian ones and are most useful when they are at their extremes. The current report is not at an extreme level; however, it is elevated and worth paying attention to as the market continues to move higher and exhibit a low level of volatility.


Tuesday, December 12, 2017

A Continued Surge In Small Business And Consumer Optimism

Sentiment for both consumers and small businesses continues to soar. Today the NFIB Small Business Optimism Index was reported at 107.5. I highlighted the surge in consumer sentiment at the end of November.


NFIB notes in its report,
"Not since the roaring Reagan economy has small business optimism been as high as it was in November, according to the National Federation of Independent Business (NFIB) Index of Small Business Optimism, released today." 
“We haven’t seen this kind of optimism in 34 years, and we’ve seen it only once in the 44 years that NFIB has been conducting this research,” said NFIB President and CEO Juanita Duggan. “Small business owners are exuberant about the economy, and they are ready to lead the U.S. economy in a period of robust growth.”
The report also indicates the current reading for November is the second highest reading in the 44-year history of the Index. Some highlights in the report:
  • Job Creation plans increased six points last month, providing more evidence of a strong labor market.
  • The number of owners who said it’s a Good Time to Expand rose four points.
  • Inventory Plans increased by three points.
  • Inventory Satisfaction increased by three points and,
  • Actual Earnings Trend moved up two points.
The significant improvement in sentiment, especially in business sentiment, has been a common theme for the last year. NFIB's report on December 2016 small business optimism saw one of the Index's largest increases. Below is a chart tracking the market's performance since NFIB's last five highest readings from December of last year. This year's market return has been the strongest.


Sentiment is an important part of investing psychology. With both consumer and small business expressing high levels of optimism, it is not surprising equity returns have been as strong as they have been this year.


Sunday, December 10, 2017

Earnings, Not Multiple Expansion, The Key To Favorable 2018 Equity Returns

It seems like an eternity since the S&P 500 Index experienced a pullback of more than 5%. In fact, the last greater than 5% pullback occurred over a year ago during the period of June 8, 2016 to June 27, 2016. This lack of downside volatility has taken place during a nearly uninterrupted increase in the market that began in February last year. Additionally, the market advance since the end of the financial crisis looks remarkable as well. Little or no downside volatility might be understandable if the equity markets were trading sideways this entire time; however, that has not been the case as can be seen below.